

CBSE Class 12 Accountancy Question Paper 2026 Set - 3 (67/1/3) is now available for download. CBSE conducted the Class 12 Accountancy examination on Feb 24, 2026, from 10:30 AM to 1:30 PM.
Also Check: CBSE Class 12 Question Paper 2026 (All Subjects)
The question paper consists of 34 questions carrying a total of 80 marks:
- Part A is compulsory for all candidates
- Part B has two options, and candidates have to attempt only one of the given options
- Option I : Analysis of Financial Statements
- Option II : Computerised Accounting
The Accountancy question paper 2026 was rated moderately difficult by the students.
CBSE Class 12 Accountancy Set - 3(67/1/3) Question Paper 2026 with Solution Pdf
| CBSE Official PDF | CD PDF | CD PDF with Solutions |
|---|---|---|
| Download official PDF 6.24 MB | Download Collegedunia PDF 0.33 MB | – |
CBSE Class 12 Accountancy 2026 Set 3 (67/1/3) Questions with Solutions
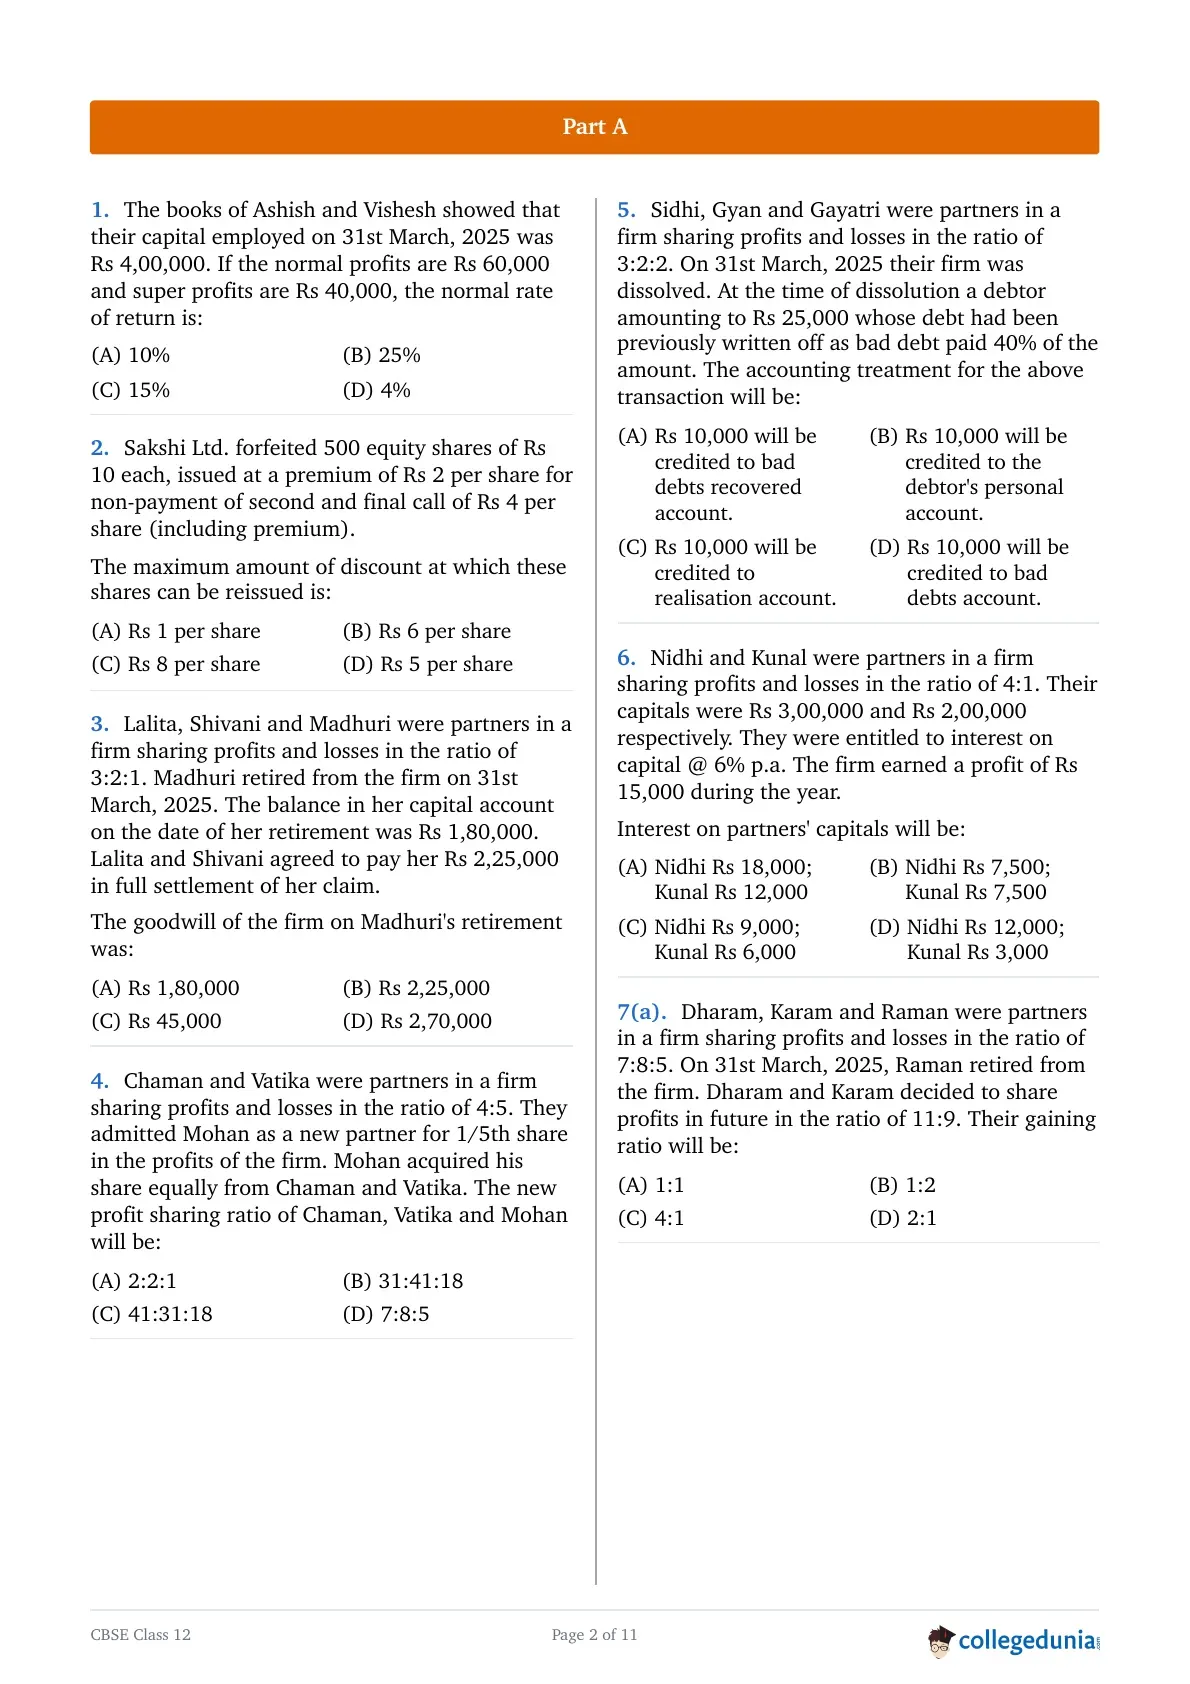
The books of Ashish and Vishesh showed that their capital employed on 31st March, 2025 was Rs 4,00,000. If the normal profits are Rs 60,000 and super profits are Rs 40,000, the normal rate of return is:
Sakshi Ltd. forfeited 500 equity shares of Rs 10 each, issued at a premium of Rs 2 per share for non-payment of second and final call of Rs 4 per share (including premium).
The maximum amount of discount at which these shares can be reissued is:
Lalita, Shivani and Madhuri were partners in a firm sharing profits and losses in the ratio of 3:2:1. Madhuri retired from the firm on 31st March, 2025. The balance in her capital account on the date of her retirement was Rs 1,80,000. Lalita and Shivani agreed to pay her Rs 2,25,000 in full settlement of her claim.
The goodwill of the firm on Madhuri's retirement was:
Chaman and Vatika were partners in a firm sharing profits and losses in the ratio of 4:5. They admitted Mohan as a new partner for 1/5th share in the profits of the firm. Mohan acquired his share equally from Chaman and Vatika. The new profit sharing ratio of Chaman, Vatika and Mohan will be:
Sidhi, Gyan and Gayatri were partners in a firm sharing profits and losses in the ratio of 3:2:2. On 31st March, 2025 their firm was dissolved. At the time of dissolution a debtor amounting to Rs 25,000 whose debt had been previously written off as bad debt paid 40% of the amount. The accounting treatment for the above transaction will be:
Nidhi and Kunal were partners in a firm sharing profits and losses in the ratio of 4:1. Their capitals were Rs 3,00,000 and Rs 2,00,000 respectively. They were entitled to interest on capital @ 6% p.a. The firm earned a profit of Rs 15,000 during the year.
Interest on partners' capitals will be:
Dharam, Karam and Raman were partners in a firm sharing profits and losses in the ratio of 7:8:5. On 31st March, 2025, Raman retired from the firm. Dharam and Karam decided to share profits in future in the ratio of 11:9. Their gaining ratio will be:
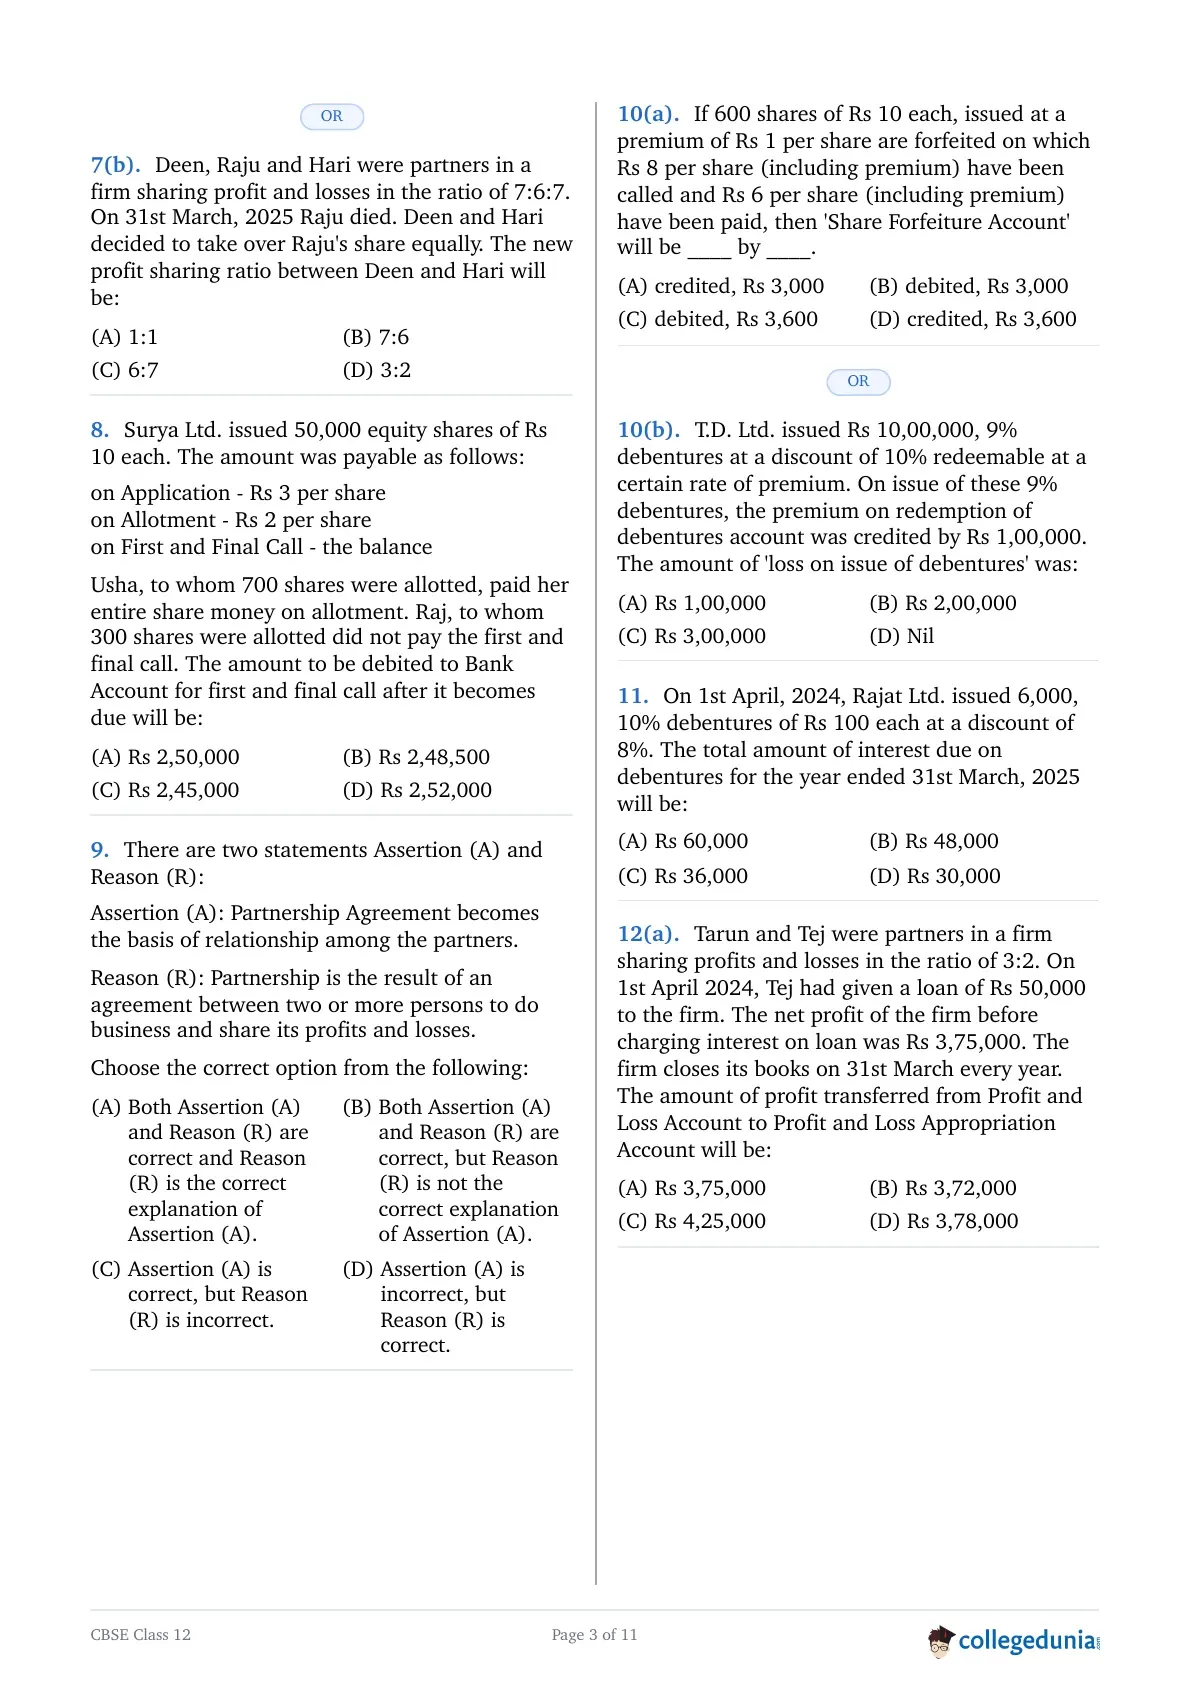
Deen, Raju and Hari were partners in a firm sharing profit and losses in the ratio of 7:6:7. On 31st March, 2025 Raju died. Deen and Hari decided to take over Raju's share equally. The new profit sharing ratio between Deen and Hari will be:
Surya Ltd. issued 50,000 equity shares of Rs 10 each. The amount was payable as follows:
on Application - Rs 3 per share
on Allotment - Rs 2 per share
on First and Final Call - the balance
Usha, to whom 700 shares were allotted, paid her entire share money on allotment. Raj, to whom 300 shares were allotted did not pay the first and final call. The amount to be debited to Bank Account for first and final call after it becomes due will be:
There are two statements Assertion (A) and Reason (R):
Assertion (A): Partnership Agreement becomes the basis of relationship among the partners.
Reason (R): Partnership is the result of an agreement between two or more persons to do business and share its profits and losses.
Choose the correct option from the following:
If 600 shares of Rs 10 each, issued at a premium of Rs 1 per share are forfeited on which Rs 8 per share (including premium) have been called and Rs 6 per share (including premium) have been paid, then 'Share Forfeiture Account' will be ____ by ____.
T.D. Ltd. issued Rs 10,00,000, 9% debentures at a discount of 10% redeemable at a certain rate of premium. On issue of these 9% debentures, the premium on redemption of debentures account was credited by Rs 1,00,000. The amount of 'loss on issue of debentures' was:
On 1st April, 2024, Rajat Ltd. issued 6,000, 10% debentures of Rs 100 each at a discount of 8%. The total amount of interest due on debentures for the year ended 31st March, 2025 will be:
Tarun and Tej were partners in a firm sharing profits and losses in the ratio of 3:2. On 1st April 2024, Tej had given a loan of Rs 50,000 to the firm. The net profit of the firm before charging interest on loan was Rs 3,75,000. The firm closes its books on 31st March every year. The amount of profit transferred from Profit and Loss Account to Profit and Loss Appropriation Account will be:
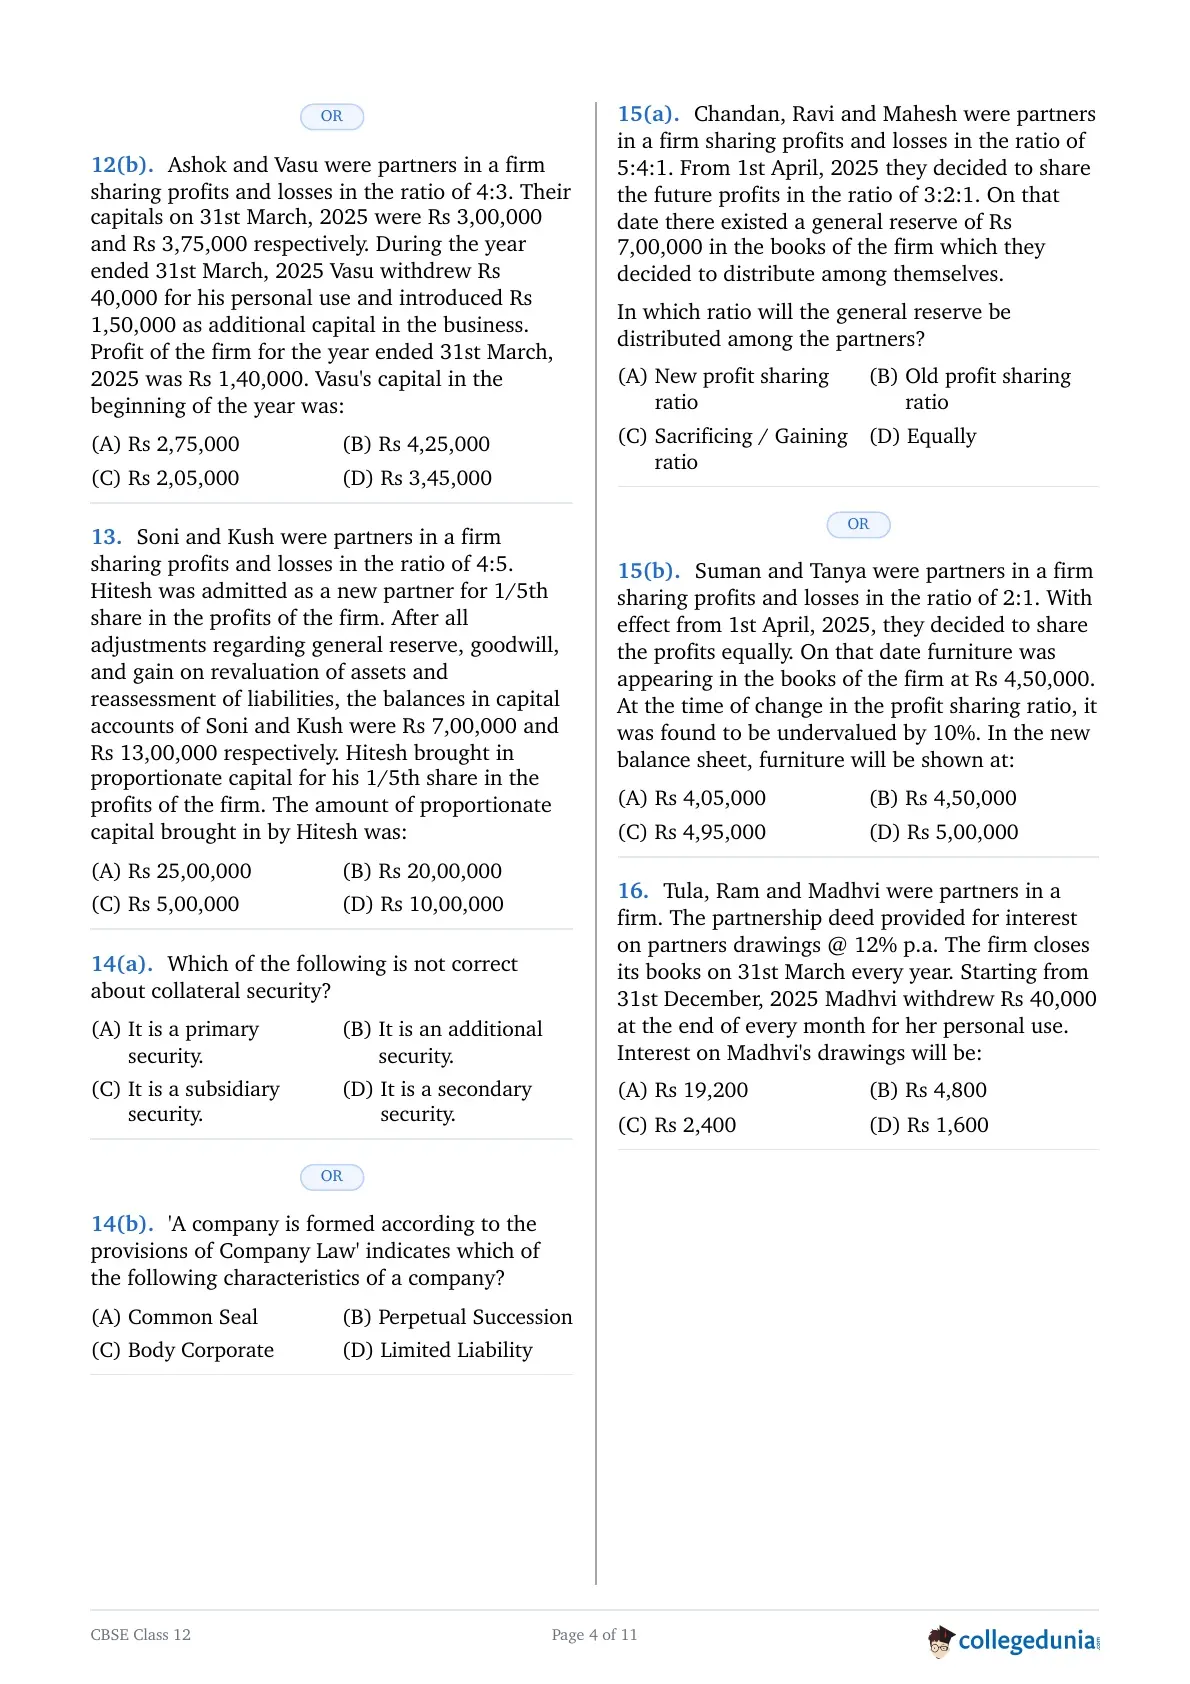
Ashok and Vasu were partners in a firm sharing profits and losses in the ratio of 4:3. Their capitals on 31st March, 2025 were Rs 3,00,000 and Rs 3,75,000 respectively. During the year ended 31st March, 2025 Vasu withdrew Rs 40,000 for his personal use and introduced Rs 1,50,000 as additional capital in the business. Profit of the firm for the year ended 31st March, 2025 was Rs 1,40,000. Vasu's capital in the beginning of the year was:
Soni and Kush were partners in a firm sharing profits and losses in the ratio of 4:5. Hitesh was admitted as a new partner for 1/5th share in the profits of the firm. After all adjustments regarding general reserve, goodwill, and gain on revaluation of assets and reassessment of liabilities, the balances in capital accounts of Soni and Kush were Rs 7,00,000 and Rs 13,00,000 respectively. Hitesh brought in proportionate capital for his 1/5th share in the profits of the firm. The amount of proportionate capital brought in by Hitesh was:
'A company is formed according to the provisions of Company Law' indicates which of the following characteristics of a company?
Chandan, Ravi and Mahesh were partners in a firm sharing profits and losses in the ratio of 5:4:1. From 1st April, 2025 they decided to share the future profits in the ratio of 3:2:1. On that date there existed a general reserve of Rs 7,00,000 in the books of the firm which they decided to distribute among themselves.
In which ratio will the general reserve be distributed among the partners?
Suman and Tanya were partners in a firm sharing profits and losses in the ratio of 2:1. With effect from 1st April, 2025, they decided to share the profits equally. On that date furniture was appearing in the books of the firm at Rs 4,50,000. At the time of change in the profit sharing ratio, it was found to be undervalued by 10%. In the new balance sheet, furniture will be shown at:
Tula, Ram and Madhvi were partners in a firm. The partnership deed provided for interest on partners drawings @ 12% p.a. The firm closes its books on 31st March every year. Starting from 31st December, 2025 Madhvi withdrew Rs 40,000 at the end of every month for her personal use. Interest on Madhvi's drawings will be:
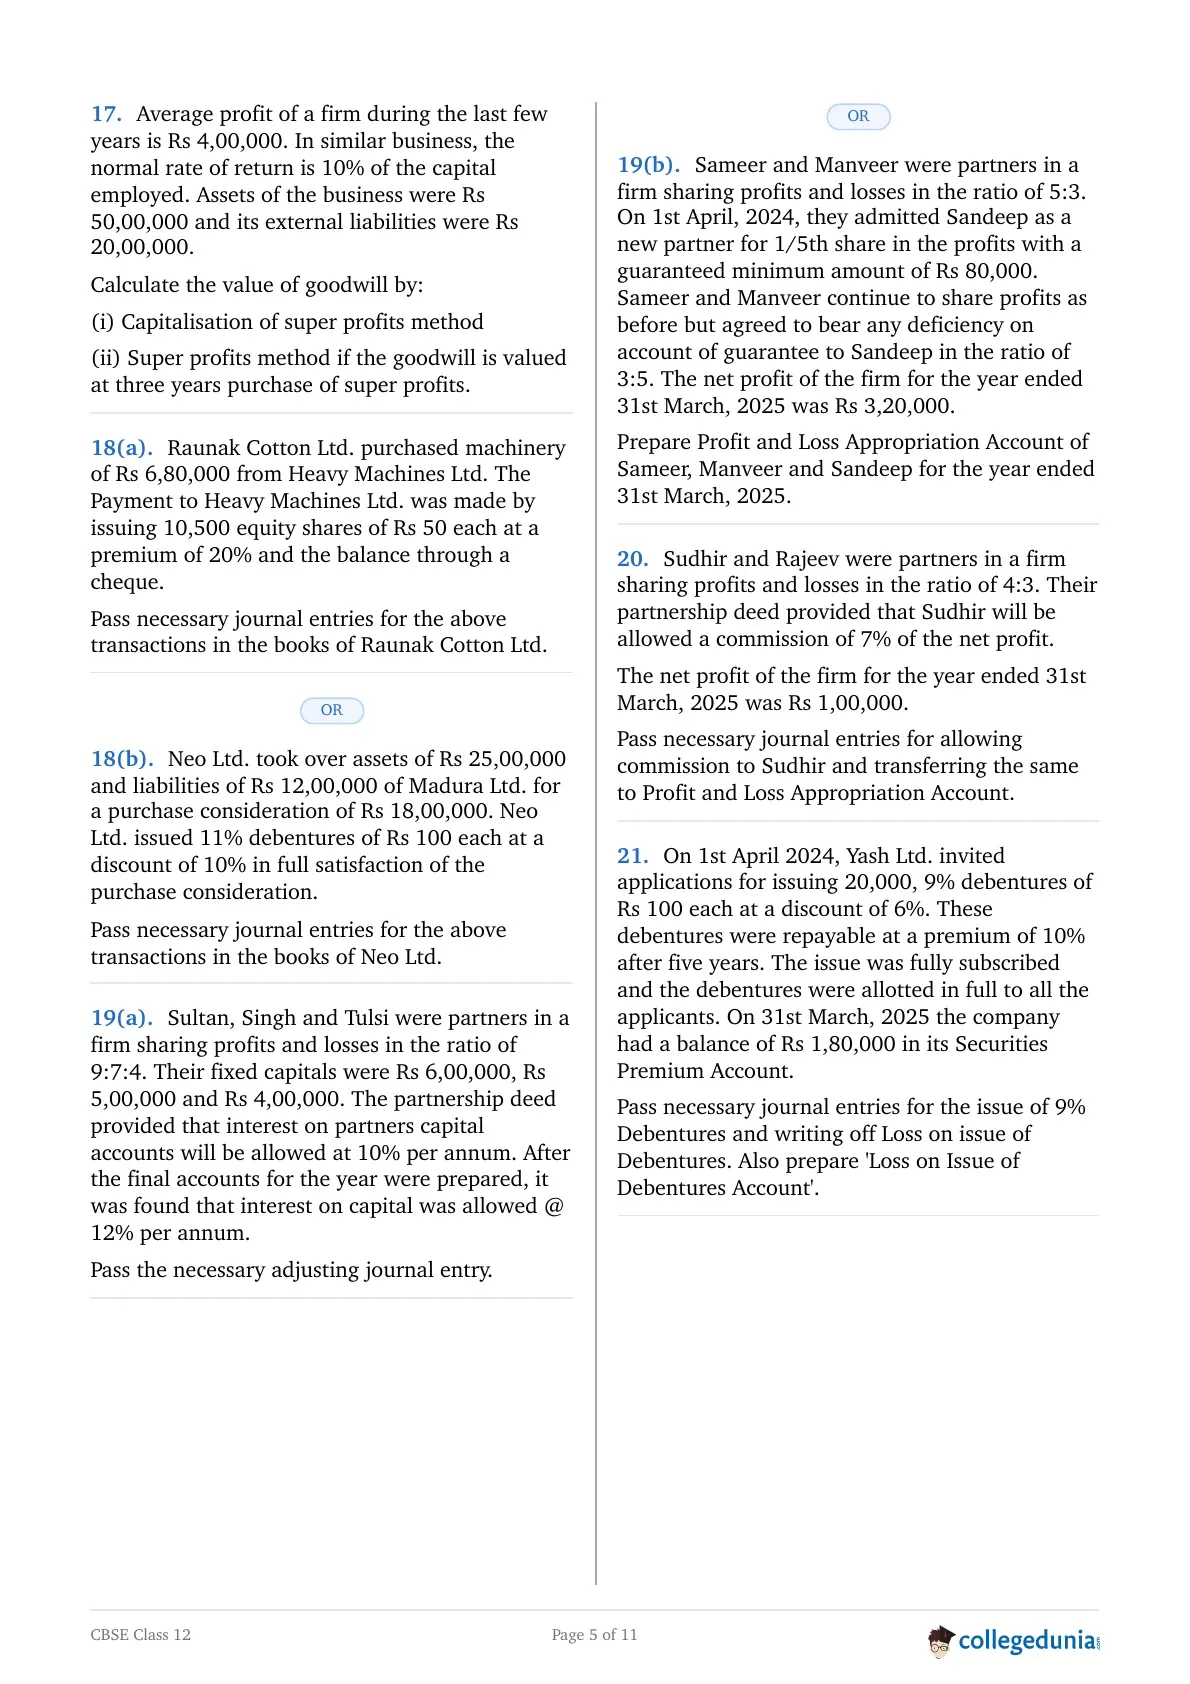
Average profit of a firm during the last few years is Rs 4,00,000. In similar business, the normal rate of return is 10% of the capital employed. Assets of the business were Rs 50,00,000 and its external liabilities were Rs 20,00,000.
Calculate the value of goodwill by:
(i) Capitalisation of super profits method
(ii) Super profits method if the goodwill is valued at three years purchase of super profits.
Raunak Cotton Ltd. purchased machinery of Rs 6,80,000 from Heavy Machines Ltd. The Payment to Heavy Machines Ltd. was made by issuing 10,500 equity shares of Rs 50 each at a premium of 20% and the balance through a cheque.
Pass necessary journal entries for the above transactions in the books of Raunak Cotton Ltd.
Neo Ltd. took over assets of Rs 25,00,000 and liabilities of Rs 12,00,000 of Madura Ltd. for a purchase consideration of Rs 18,00,000. Neo Ltd. issued 11% debentures of Rs 100 each at a discount of 10% in full satisfaction of the purchase consideration.
Pass necessary journal entries for the above transactions in the books of Neo Ltd.
Sultan, Singh and Tulsi were partners in a firm sharing profits and losses in the ratio of 9:7:4. Their fixed capitals were Rs 6,00,000, Rs 5,00,000 and Rs 4,00,000. The partnership deed provided that interest on partners capital accounts will be allowed at 10% per annum. After the final accounts for the year were prepared, it was found that interest on capital was allowed @ 12% per annum.
Pass the necessary adjusting journal entry.
Sameer and Manveer were partners in a firm sharing profits and losses in the ratio of 5:3. On 1st April, 2024, they admitted Sandeep as a new partner for 1/5th share in the profits with a guaranteed minimum amount of Rs 80,000. Sameer and Manveer continue to share profits as before but agreed to bear any deficiency on account of guarantee to Sandeep in the ratio of 3:5. The net profit of the firm for the year ended 31st March, 2025 was Rs 3,20,000.
Prepare Profit and Loss Appropriation Account of Sameer, Manveer and Sandeep for the year ended 31st March, 2025.
Sudhir and Rajeev were partners in a firm sharing profits and losses in the ratio of 4:3. Their partnership deed provided that Sudhir will be allowed a commission of 7% of the net profit.
The net profit of the firm for the year ended 31st March, 2025 was Rs 1,00,000.
Pass necessary journal entries for allowing commission to Sudhir and transferring the same to Profit and Loss Appropriation Account.
On 1st April 2024, Yash Ltd. invited applications for issuing 20,000, 9% debentures of Rs 100 each at a discount of 6%. These debentures were repayable at a premium of 10% after five years. The issue was fully subscribed and the debentures were allotted in full to all the applicants. On 31st March, 2025 the company had a balance of Rs 1,80,000 in its Securities Premium Account.
Pass necessary journal entries for the issue of 9% Debentures and writing off Loss on issue of Debentures. Also prepare 'Loss on Issue of Debentures Account'.
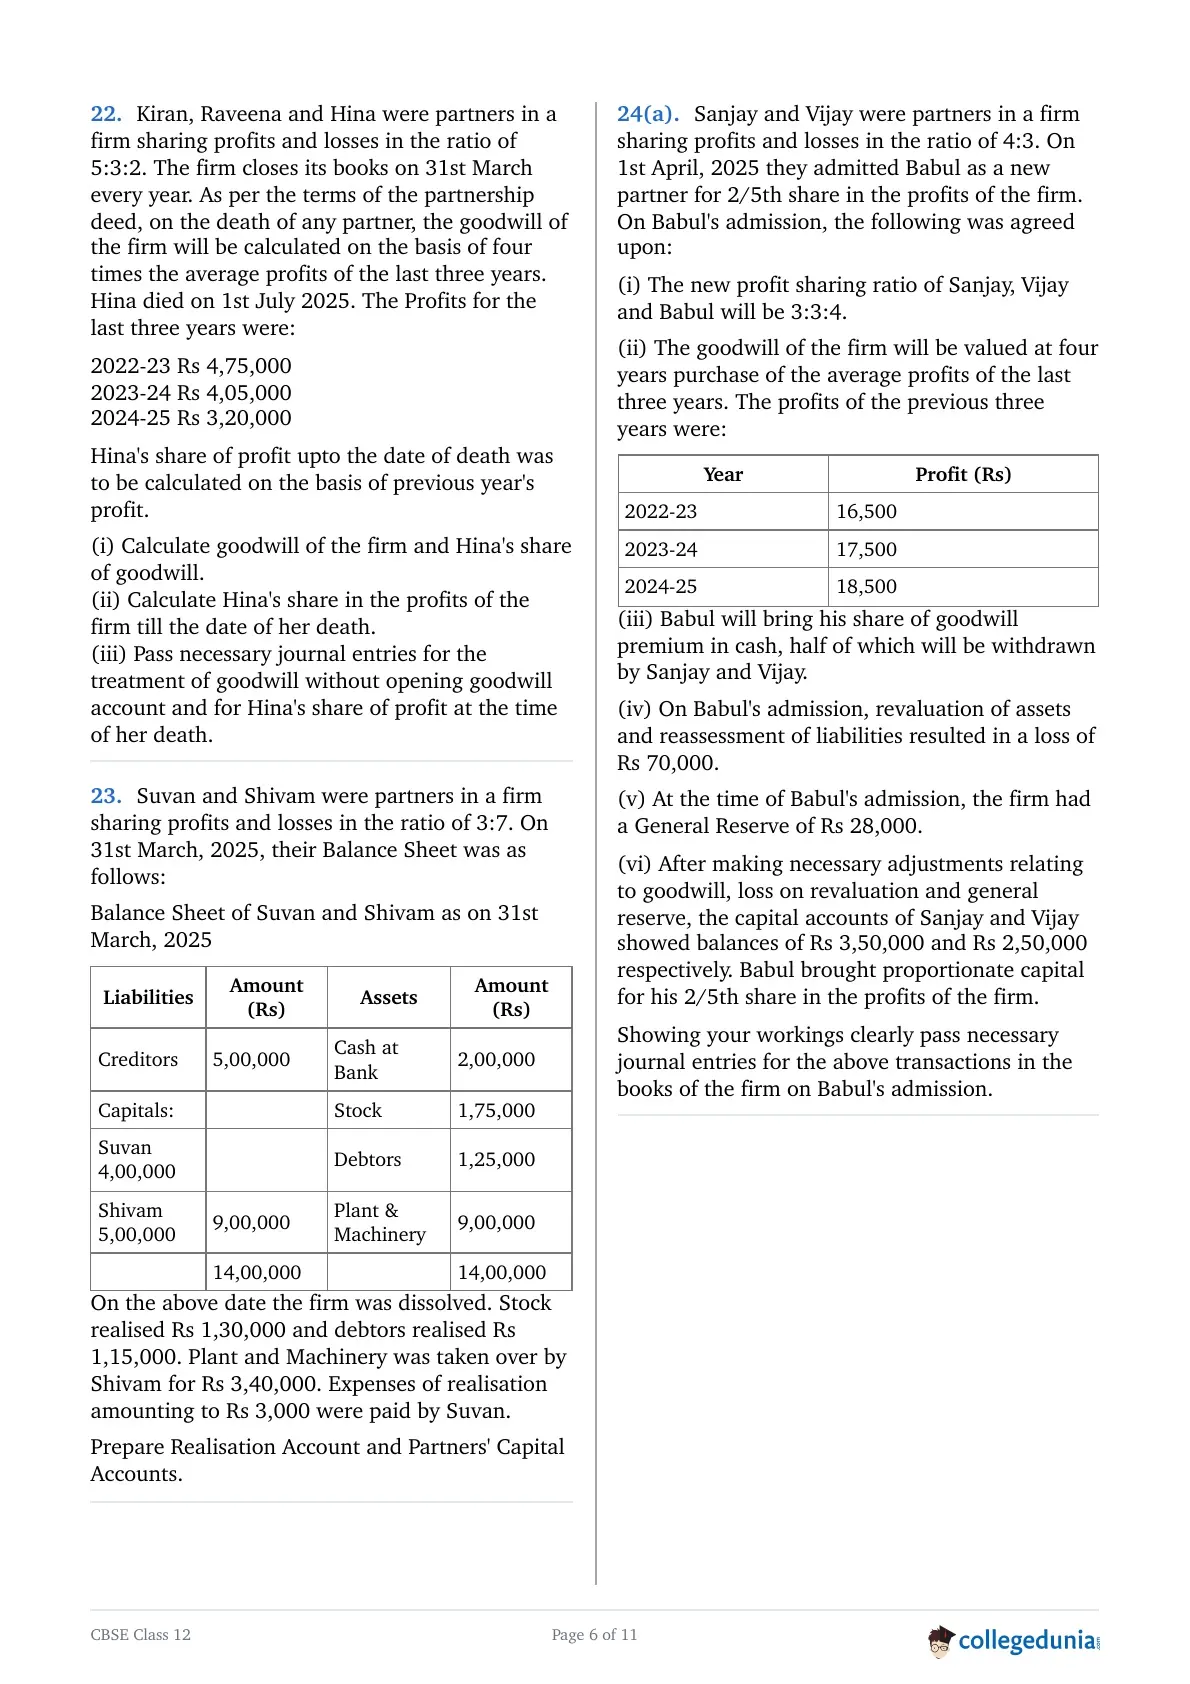
Kiran, Raveena and Hina were partners in a firm sharing profits and losses in the ratio of 5:3:2. The firm closes its books on 31st March every year. As per the terms of the partnership deed, on the death of any partner, the goodwill of the firm will be calculated on the basis of four times the average profits of the last three years. Hina died on 1st July 2025. The Profits for the last three years were:
2022-23 Rs 4,75,000
2023-24 Rs 4,05,000
2024-25 Rs 3,20,000
Hina's share of profit upto the date of death was to be calculated on the basis of previous year's profit.
(i) Calculate goodwill of the firm and Hina's share of goodwill.
(ii) Calculate Hina's share in the profits of the firm till the date of her death.
(iii) Pass necessary journal entries for the treatment of goodwill without opening goodwill account and for Hina's share of profit at the time of her death.
Suvan and Shivam were partners in a firm sharing profits and losses in the ratio of 3:7. On 31st March, 2025, their Balance Sheet was as follows:
Balance Sheet of Suvan and Shivam as on 31st March, 2025
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
|---|---|---|---|
| Creditors | 5,00,000 | Cash at Bank | 2,00,000 |
| Capitals: | Stock | 1,75,000 | |
| Suvan 4,00,000 | Debtors | 1,25,000 | |
| Shivam 5,00,000 | 9,00,000 | Plant & Machinery | 9,00,000 |
| 14,00,000 | 14,00,000 |
On the above date the firm was dissolved. Stock realised Rs 1,30,000 and debtors realised Rs 1,15,000. Plant and Machinery was taken over by Shivam for Rs 3,40,000. Expenses of realisation amounting to Rs 3,000 were paid by Suvan.
Prepare Realisation Account and Partners' Capital Accounts.
Sanjay and Vijay were partners in a firm sharing profits and losses in the ratio of 4:3. On 1st April, 2025 they admitted Babul as a new partner for 2/5th share in the profits of the firm. On Babul's admission, the following was agreed upon:
(i) The new profit sharing ratio of Sanjay, Vijay and Babul will be 3:3:4.
(ii) The goodwill of the firm will be valued at four years purchase of the average profits of the last three years. The profits of the previous three years were:
| Year | Profit (Rs) |
|---|---|
| 2022-23 | 16,500 |
| 2023-24 | 17,500 |
| 2024-25 | 18,500 |
(iii) Babul will bring his share of goodwill premium in cash, half of which will be withdrawn by Sanjay and Vijay.
(iv) On Babul's admission, revaluation of assets and reassessment of liabilities resulted in a loss of Rs 70,000.
(v) At the time of Babul's admission, the firm had a General Reserve of Rs 28,000.
(vi) After making necessary adjustments relating to goodwill, loss on revaluation and general reserve, the capital accounts of Sanjay and Vijay showed balances of Rs 3,50,000 and Rs 2,50,000 respectively. Babul brought proportionate capital for his 2/5th share in the profits of the firm.
Showing your workings clearly pass necessary journal entries for the above transactions in the books of the firm on Babul's admission.
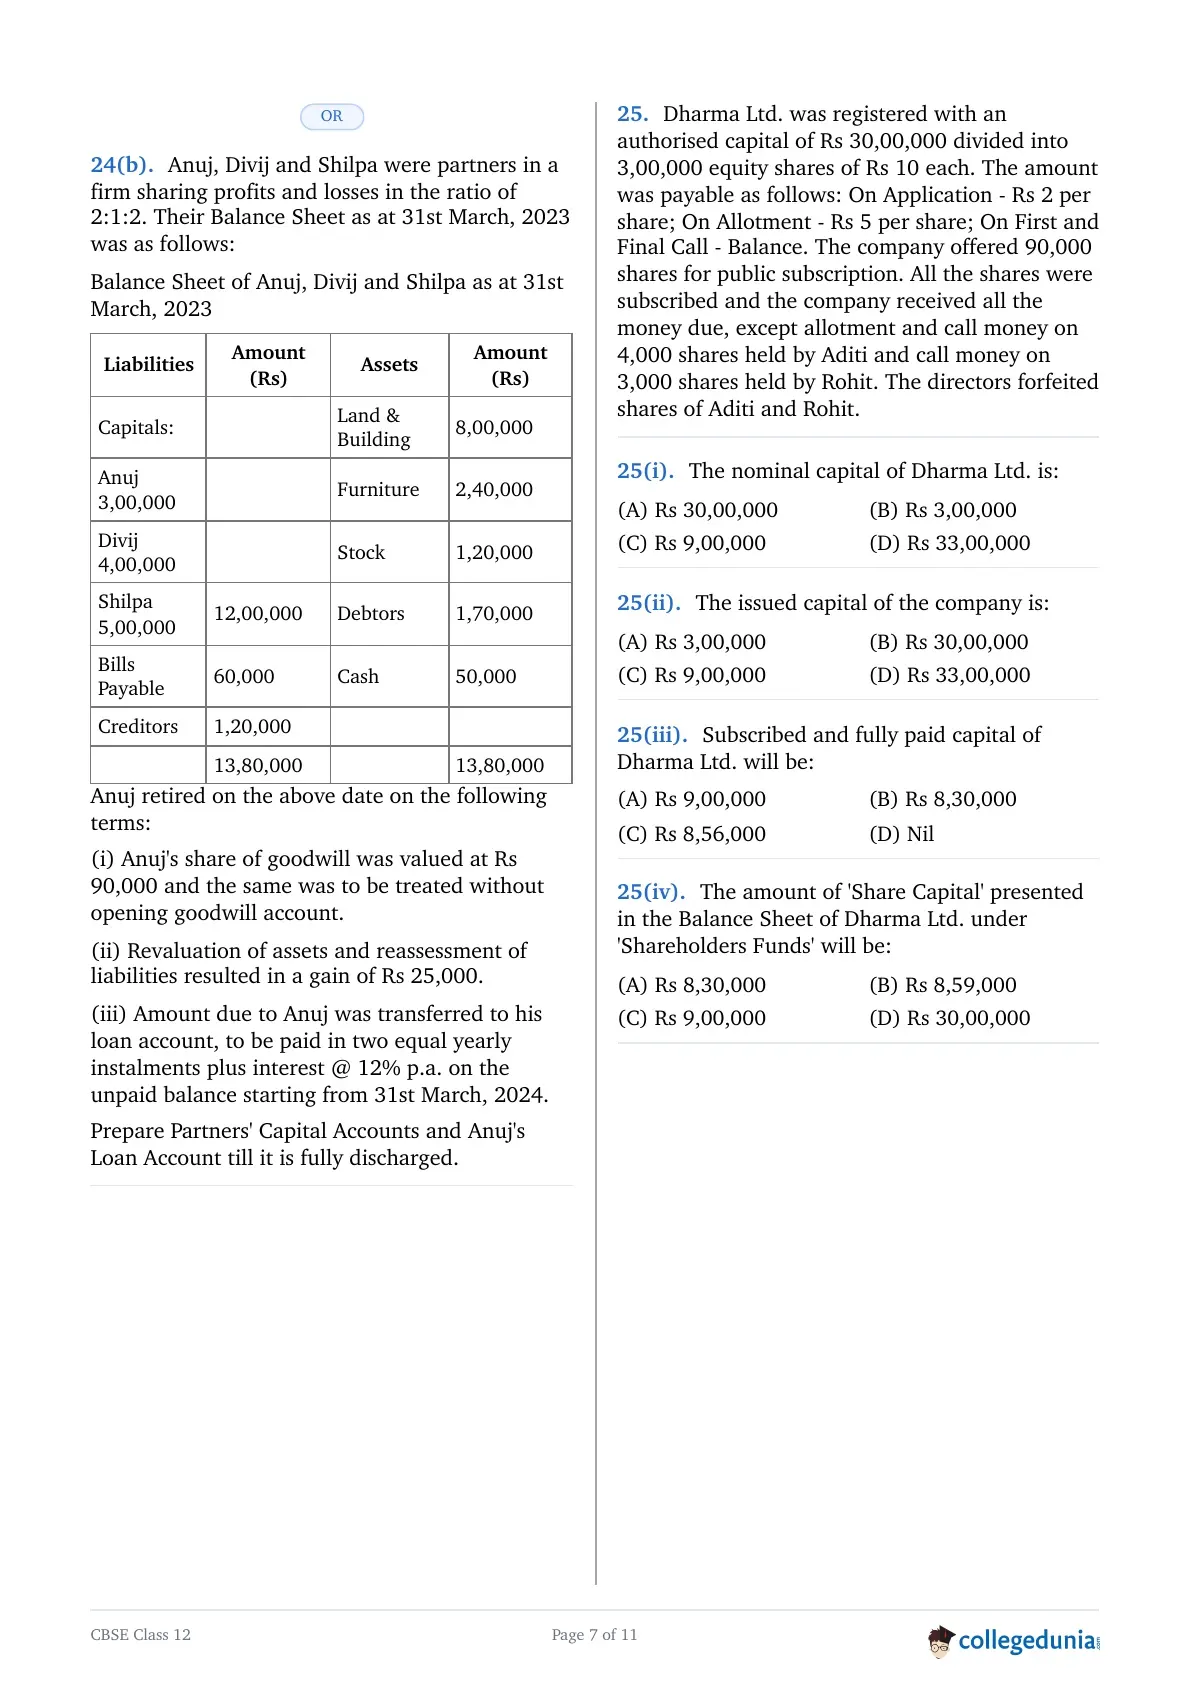
Anuj, Divij and Shilpa were partners in a firm sharing profits and losses in the ratio of 2:1:2. Their Balance Sheet as at 31st March, 2023 was as follows:
Balance Sheet of Anuj, Divij and Shilpa as at 31st March, 2023
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
|---|---|---|---|
| Capitals: | Land & Building | 8,00,000 | |
| Anuj 3,00,000 | Furniture | 2,40,000 | |
| Divij 4,00,000 | Stock | 1,20,000 | |
| Shilpa 5,00,000 | 12,00,000 | Debtors | 1,70,000 |
| Bills Payable | 60,000 | Cash | 50,000 |
| Creditors | 1,20,000 | ||
| 13,80,000 | 13,80,000 |
Anuj retired on the above date on the following terms:
(i) Anuj's share of goodwill was valued at Rs 90,000 and the same was to be treated without opening goodwill account.
(ii) Revaluation of assets and reassessment of liabilities resulted in a gain of Rs 25,000.
(iii) Amount due to Anuj was transferred to his loan account, to be paid in two equal yearly instalments plus interest @ 12% p.a. on the unpaid balance starting from 31st March, 2024.
Prepare Partners' Capital Accounts and Anuj's Loan Account till it is fully discharged.
Comprehension:
Dharma Ltd. was registered with an authorised capital of Rs 30,00,000 divided into 3,00,000 equity shares of Rs 10 each. The amount was payable as follows: On Application - Rs 2 per share; On Allotment - Rs 5 per share; On First and Final Call - Balance. The company offered
Read More
90,000 shares for public subscription. All the shares were subscribed and the company received all the money due, except allotment and call money on 4,000 shares held by Aditi and call money on 3,000 shares held by Rohit. The directors forfeited shares of Aditi and Rohit.The amount of 'Share Capital' presented in the Balance Sheet of Dharma Ltd. under 'Shareholders Funds' will be:
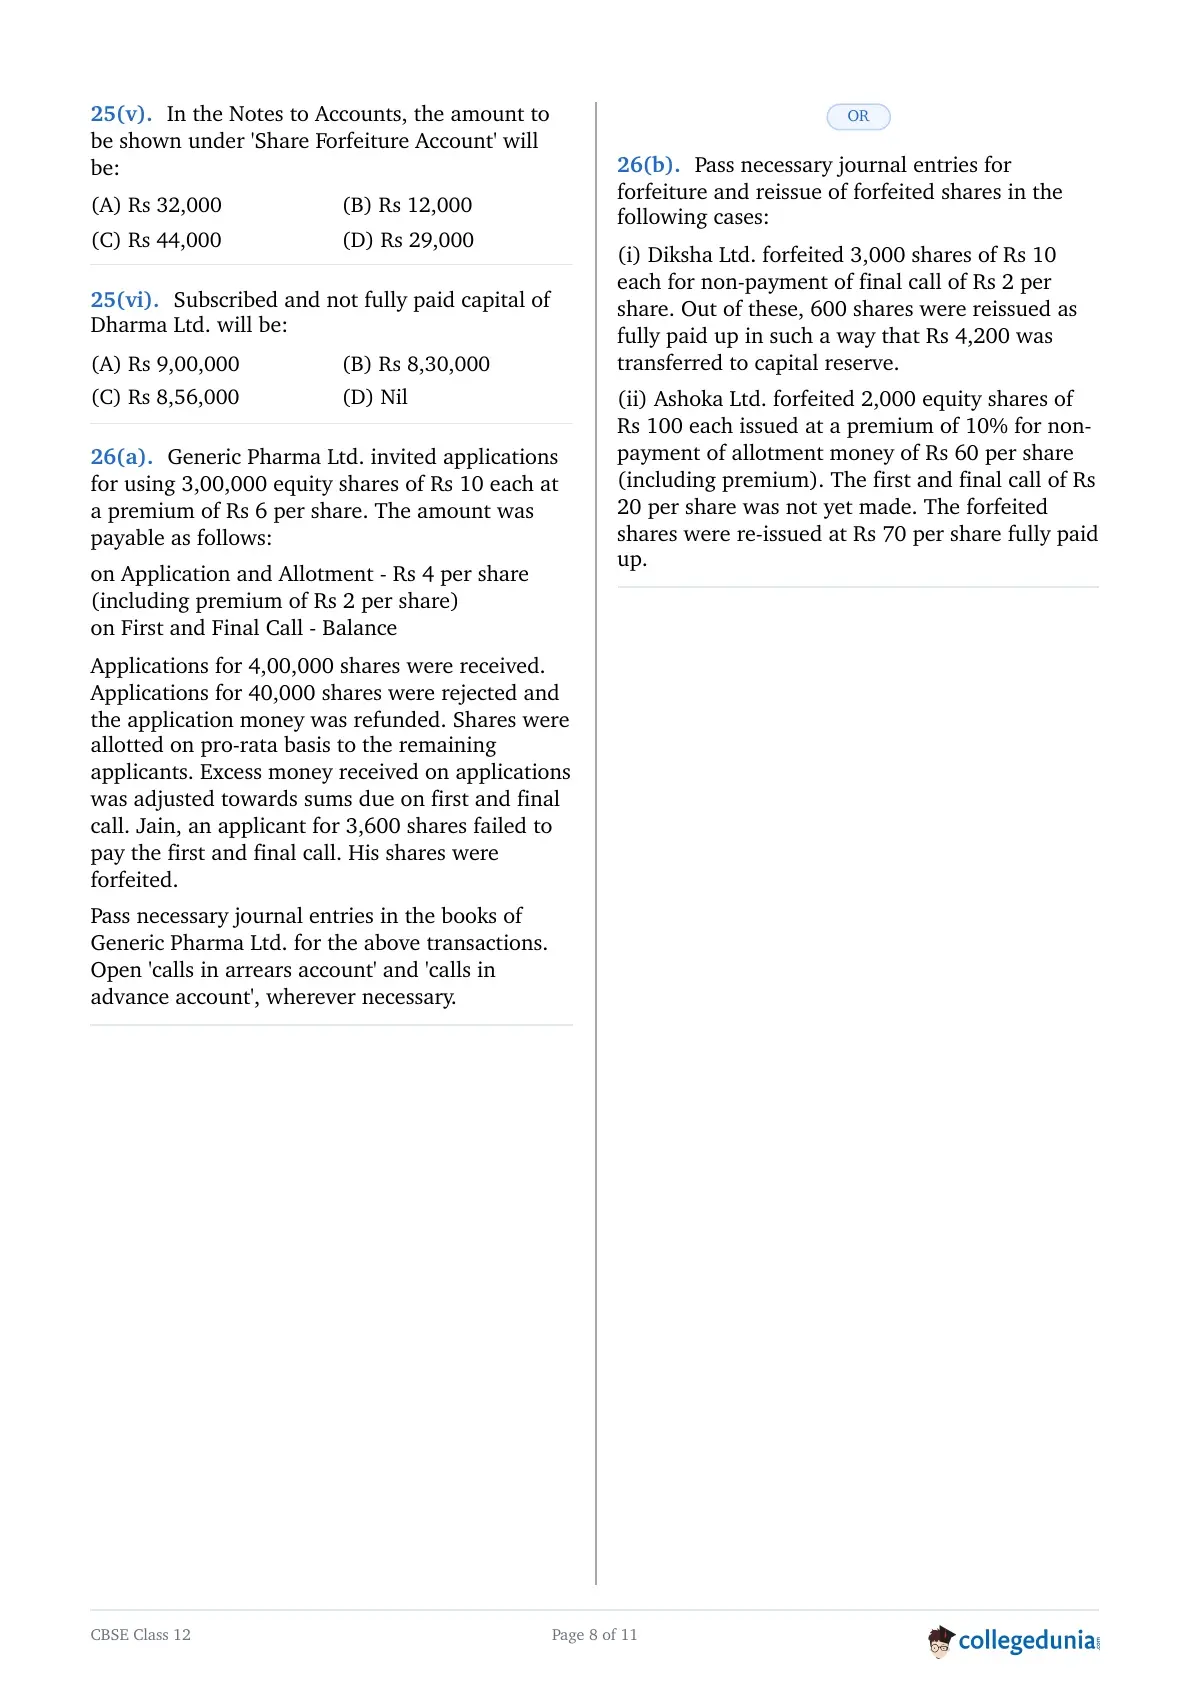
In the Notes to Accounts, the amount to be shown under 'Share Forfeiture Account' will be:
Generic Pharma Ltd. invited applications for using 3,00,000 equity shares of Rs 10 each at a premium of Rs 6 per share. The amount was payable as follows:
on Application and Allotment - Rs 4 per share (including premium of Rs 2 per share)
on First and Final Call - Balance
Applications for 4,00,000 shares were received. Applications for 40,000 shares were rejected and the application money was refunded. Shares were allotted on pro-rata basis to the remaining applicants. Excess money received on applications was adjusted towards sums due on first and final call. Jain, an applicant for 3,600 shares failed to pay the first and final call. His shares were forfeited.
Pass necessary journal entries in the books of Generic Pharma Ltd. for the above transactions. Open 'calls in arrears account' and 'calls in advance account', wherever necessary.
Pass necessary journal entries for forfeiture and reissue of forfeited shares in the following cases:
(i) Diksha Ltd. forfeited 3,000 shares of Rs 10 each for non-payment of final call of Rs 2 per share. Out of these, 600 shares were reissued as fully paid up in such a way that Rs 4,200 was transferred to capital reserve.
(ii) Ashoka Ltd. forfeited 2,000 equity shares of Rs 100 each issued at a premium of 10% for non-payment of allotment money of Rs 60 per share (including premium). The first and final call of Rs 20 per share was not yet made. The forfeited shares were re-issued at Rs 70 per share fully paid up.
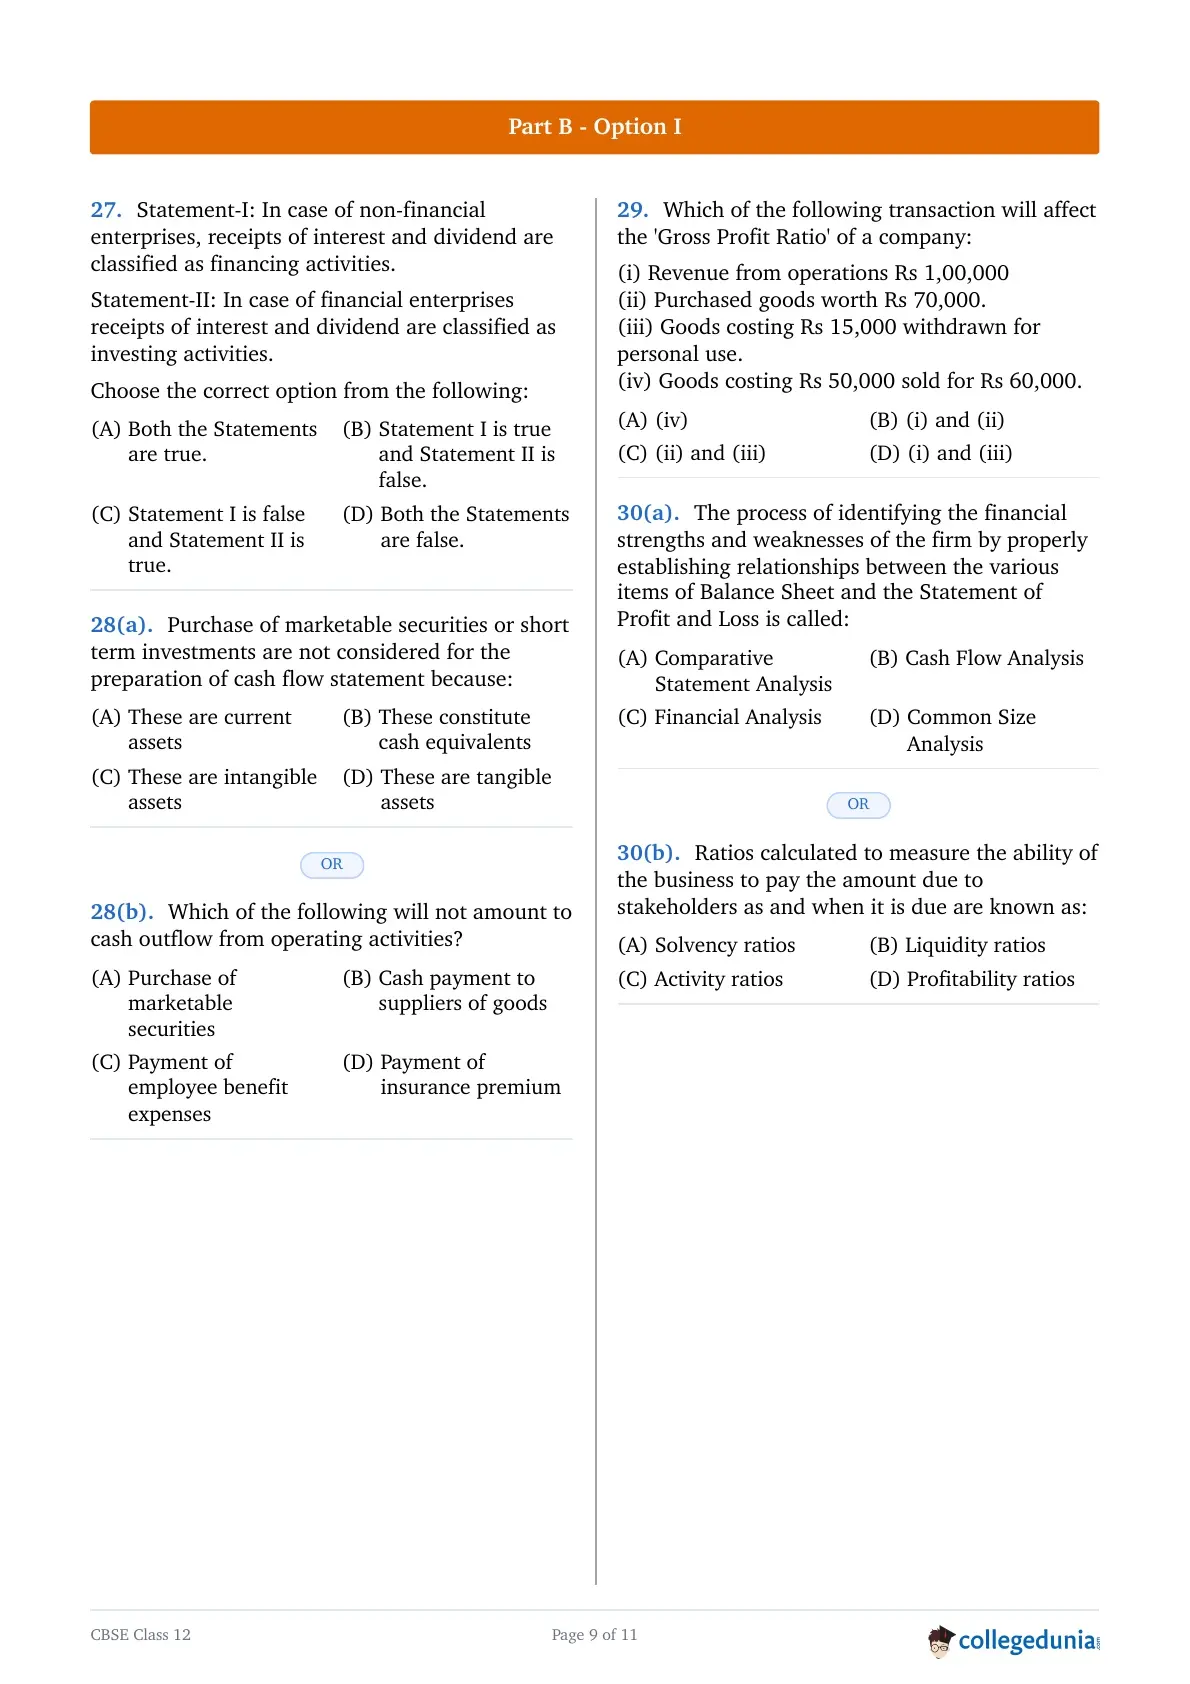
Statement-I: In case of non-financial enterprises, receipts of interest and dividend are classified as financing activities.
Statement-II: In case of financial enterprises receipts of interest and dividend are classified as investing activities.
Choose the correct option from the following:
Purchase of marketable securities or short term investments are not considered for the preparation of cash flow statement because:
Which of the following will not amount to cash outflow from operating activities?
Which of the following transaction will affect the 'Gross Profit Ratio' of a company:
(i) Revenue from operations Rs 1,00,000
(ii) Purchased goods worth Rs 70,000.
(iii) Goods costing Rs 15,000 withdrawn for personal use.
(iv) Goods costing Rs 50,000 sold for Rs 60,000.
The process of identifying the financial strengths and weaknesses of the firm by properly establishing relationships between the various items of Balance Sheet and the Statement of Profit and Loss is called:
Ratios calculated to measure the ability of the business to pay the amount due to stakeholders as and when it is due are known as:
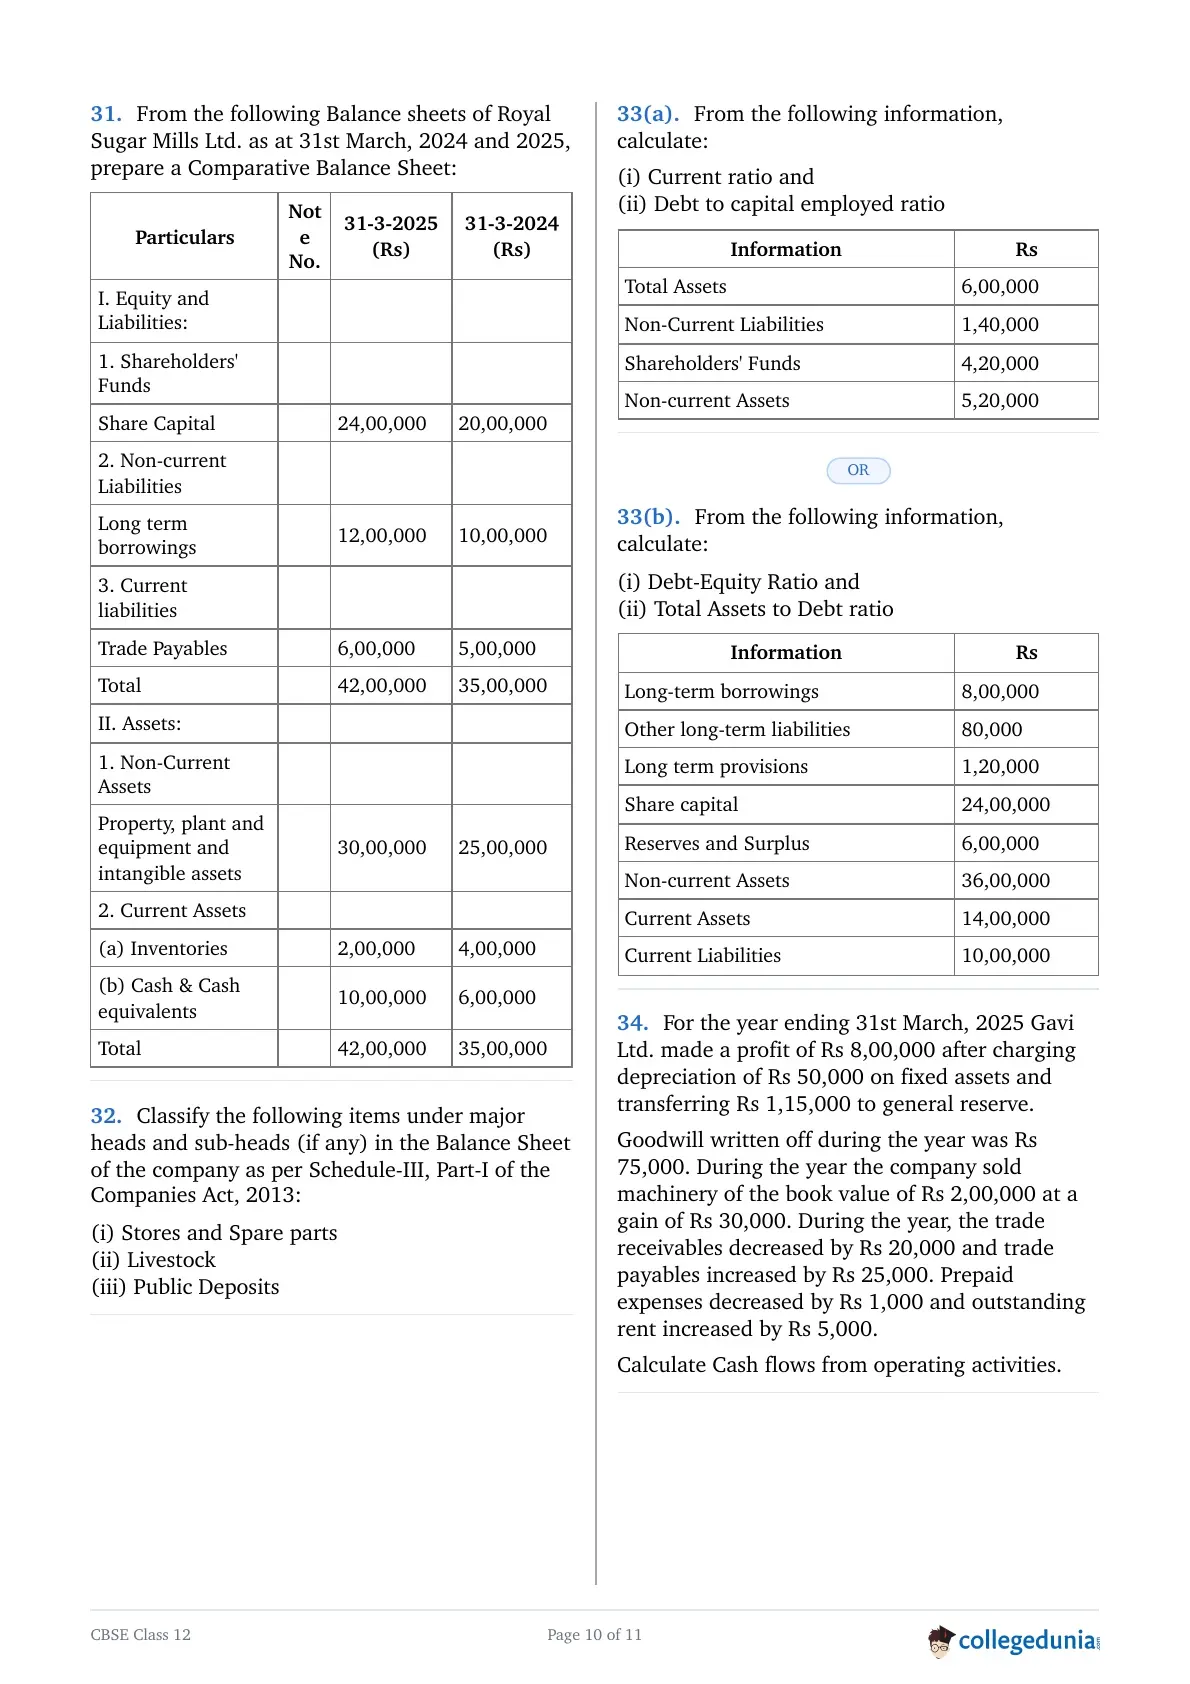
From the following Balance sheets of Royal Sugar Mills Ltd. as at 31st March, 2024 and 2025, prepare a Comparative Balance Sheet:
| Particulars | Note No. | 31-3-2025 (Rs) | 31-3-2024 (Rs) |
|---|---|---|---|
| I. Equity and Liabilities: | |||
| 1. Shareholders' Funds | |||
| Share Capital | 24,00,000 | 20,00,000 | |
| 2. Non-current Liabilities | |||
| Long term borrowings | 12,00,000 | 10,00,000 | |
| 3. Current liabilities | |||
| Trade Payables | 6,00,000 | 5,00,000 | |
| Total | 42,00,000 | 35,00,000 | |
| II. Assets: | |||
| 1. Non-Current Assets | |||
| Property, plant and equipment and intangible assets | 30,00,000 | 25,00,000 | |
| 2. Current Assets | |||
| (a) Inventories | 2,00,000 | 4,00,000 | |
| (b) Cash & Cash equivalents | 10,00,000 | 6,00,000 | |
| Total | 42,00,000 | 35,00,000 |
Classify the following items under major heads and sub-heads (if any) in the Balance Sheet of the company as per Schedule-III, Part-I of the Companies Act, 2013:
(i) Stores and Spare parts
(ii) Livestock
(iii) Public Deposits
From the following information, calculate:
(i) Current ratio and
(ii) Debt to capital employed ratio
| Information | Rs |
|---|---|
| Total Assets | 6,00,000 |
| Non-Current Liabilities | 1,40,000 |
| Shareholders' Funds | 4,20,000 |
| Non-current Assets | 5,20,000 |
From the following information, calculate:
(i) Debt-Equity Ratio and
(ii) Total Assets to Debt ratio
| Information | Rs |
|---|---|
| Long-term borrowings | 8,00,000 |
| Other long-term liabilities | 80,000 |
| Long term provisions | 1,20,000 |
| Share capital | 24,00,000 |
| Reserves and Surplus | 6,00,000 |
| Non-current Assets | 36,00,000 |
| Current Assets | 14,00,000 |
| Current Liabilities | 10,00,000 |
For the year ending 31st March, 2025 Gavi Ltd. made a profit of Rs 8,00,000 after charging depreciation of Rs 50,000 on fixed assets and transferring Rs 1,15,000 to general reserve.
Goodwill written off during the year was Rs 75,000. During the year the company sold machinery of the book value of Rs 2,00,000 at a gain of Rs 30,000. During the year, the trade receivables decreased by Rs 20,000 and trade payables increased by Rs 25,000. Prepaid expenses decreased by Rs 1,000 and outstanding rent increased by Rs 5,000.
Calculate Cash flows from operating activities.
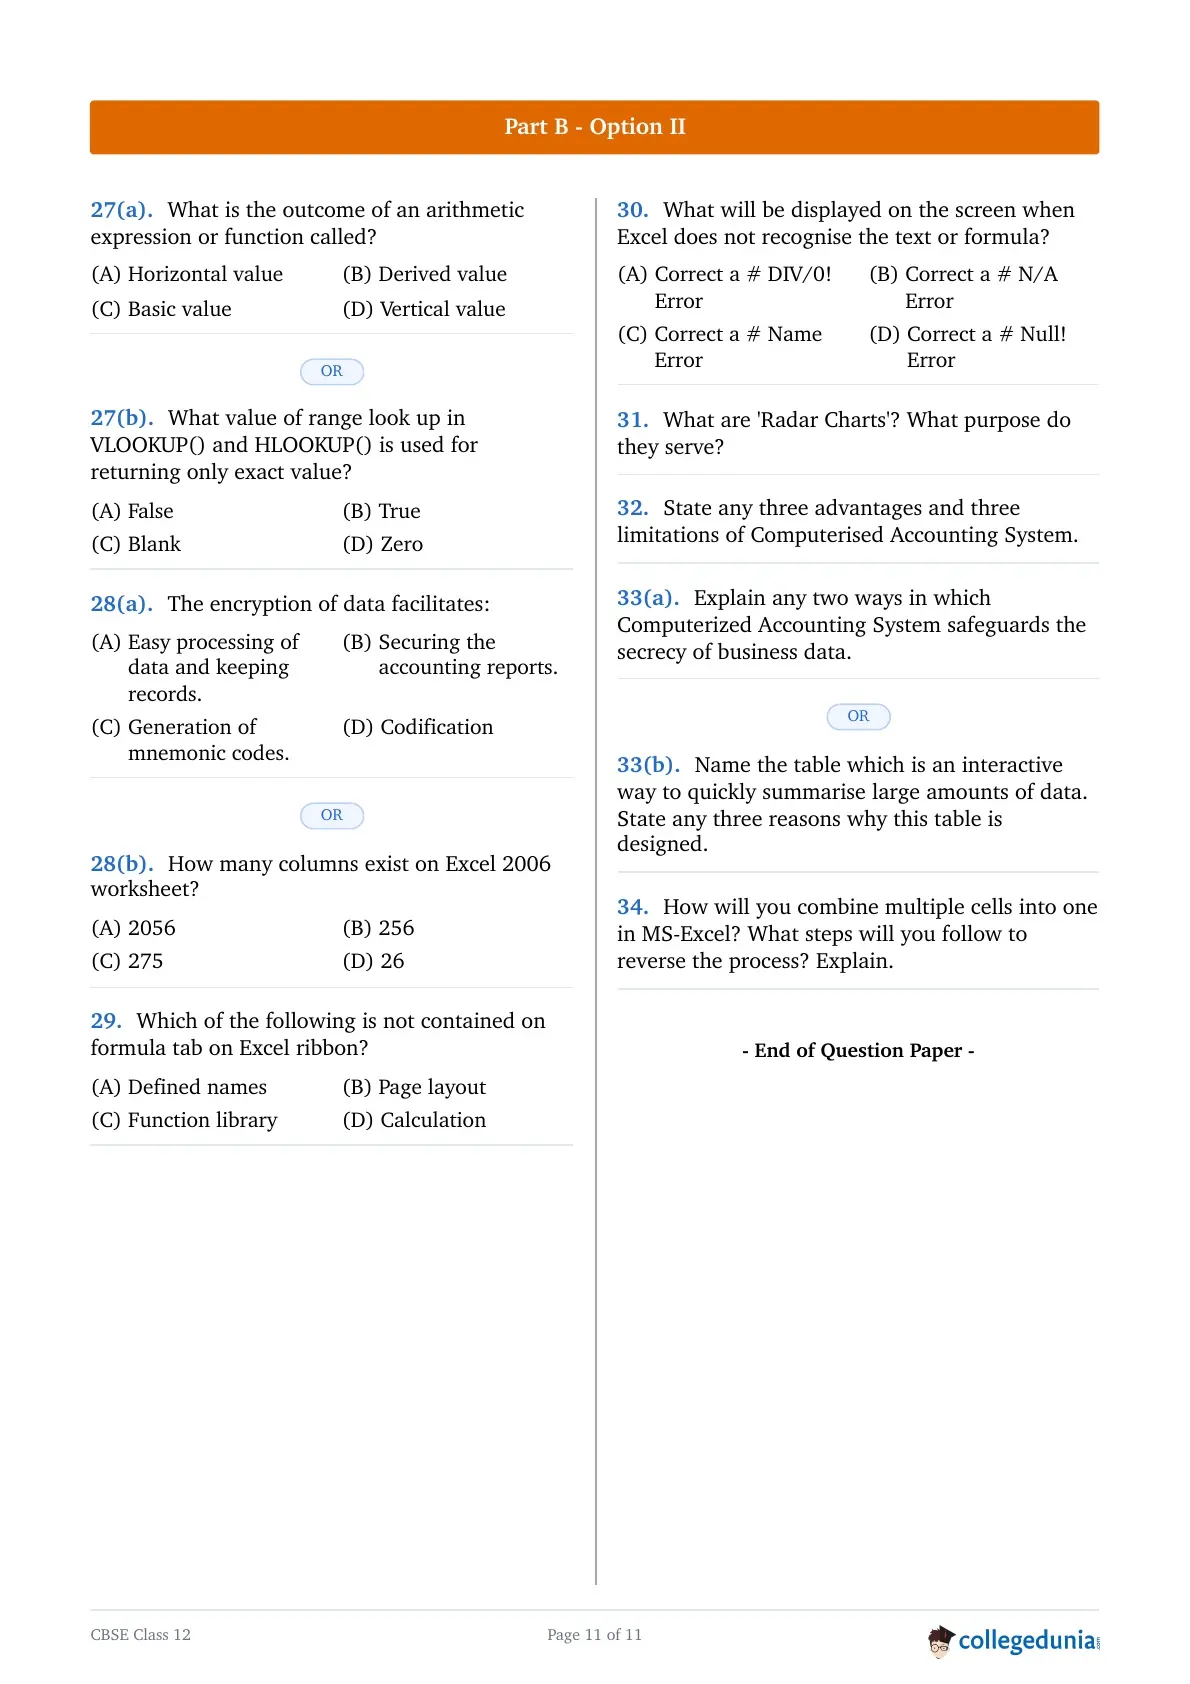
What is the outcome of an arithmetic expression or function called?
What value of range look up in VLOOKUP() and HLOOKUP() is used for returning only exact value?
Which of the following is not contained on formula tab on Excel ribbon?
What will be displayed on the screen when Excel does not recognise the text or formula?
State any three advantages and three limitations of Computerised Accounting System.
Explain any two ways in which Computerized Accounting System safeguards the secrecy of business data.
Name the table which is an interactive way to quickly summarise large amounts of data. State any three reasons why this table is designed.
How will you combine multiple cells into one in MS-Excel? What steps will you follow to reverse the process? Explain.
CBSE Class 12 Accountancy Question Paper Pattern and Marking Scheme
The CBSE Class 12 Accountancy 2026 theory paper is of 80 marks and has 34 questions, all compulsory: Part A (60 marks) is common and Part B (20 marks) has two options, Option I (Analysis of Financial Statements) and Option II (Computerised Accounting), of which a candidate attempts only one. Internal choice (OR) is given in several questions. The tables below give the paper pattern and the marking rules from the official CBSE question paper and marking scheme.
CBSE Class 12 Accountancy Question Paper Pattern 2026
| Part | Questions | Question Type | Marks per Question | Marks |
|---|---|---|---|---|
| Part A | Q1 - Q16 | Multiple choice questions (MCQs) | 1 | 16 |
| Part A | Q17 - Q20 | Short answer questions | 3 | 12 |
| Part A | Q21 - Q22 | Short answer questions | 4 | 8 |
| Part A | Q23 - Q24 | Long answer questions | 6 | 12 |
| Part A | Q25 | Case-based questions (6 MCQs of 1 mark each) | 1 | 6 |
| Part A | Q26 | Long answer questions | 6 | 6 |
| Part B | Q27 - Q30 | Multiple choice questions (MCQs) | 1 | 4 |
| Part B | Q31 - Q32 | Short answer questions | 3 | 6 |
| Part B | Q33 | Short answer questions | 4 | 4 |
| Part B | Q34 | Long answer questions | 6 | 6 |
| Total | 34 questions | 80 |
CBSE Class 12 Accountancy Marking Scheme 2026
| Marking point | How it is applied |
|---|---|
| Value-point marking | Marks are awarded against the value points (steps) given in the official marking scheme; the marks of an answer are split across its parts and value points. |
| Own expression | The marking scheme carries suggested value points only. A correct answer in the student's own words is awarded due marks. |
| Competency-based questions | If a competency-based answer is not from the marking scheme but shows the correct competency, due marks are awarded. |
| Errors | An error is penalised only once; no marks are deducted for its cumulative effect. |
| Incorrect answer | A totally incorrect answer is awarded zero (0) marks. |
| Choice (OR) questions | If both options of a question with internal choice are attempted, marks are awarded for both and the higher score is taken; if only one option is attempted, the other is marked NA (not attempted). |
| Part B options | If a candidate attempts both Option I and Option II of Part B, the higher of the two scores is taken and the other response is disregarded. |
| Scale of marks | The full scale of 0 to 80 marks is used and full marks are awarded whenever the answer deserves them. |
CBSE Class 12 Accountancy Unit-Wise Weightage
| Part | Units / Chapters | Marks |
|---|---|---|
| Part A – Accounting for Partnership Firms and Companies (60 Marks) | Fundamentals of Partnership Firms | 6 |
| Reconstitution of Partnership (Admission, Retirement, Death, Change in Ratio) | 18 | |
| Dissolution of Partnership Firm | 6 | |
| Accounting for Share Capital | 8 | |
| Accounting for Debentures | 12 | |
| Total Part A | — | 60 |
| Part B – Financial Statement Analysis OR Computerised Accounting (20 Marks) | Analysis of Financial Statements (including Cash Flow Statement, Ratio Analysis) OR Computerised Accounting | 20 |
| Total Part B | — | 20 |
| Part C – Project Work | Project File (12) + Viva Voce (8) | 20 |
| Grand Total | — | 100 |


Comments