

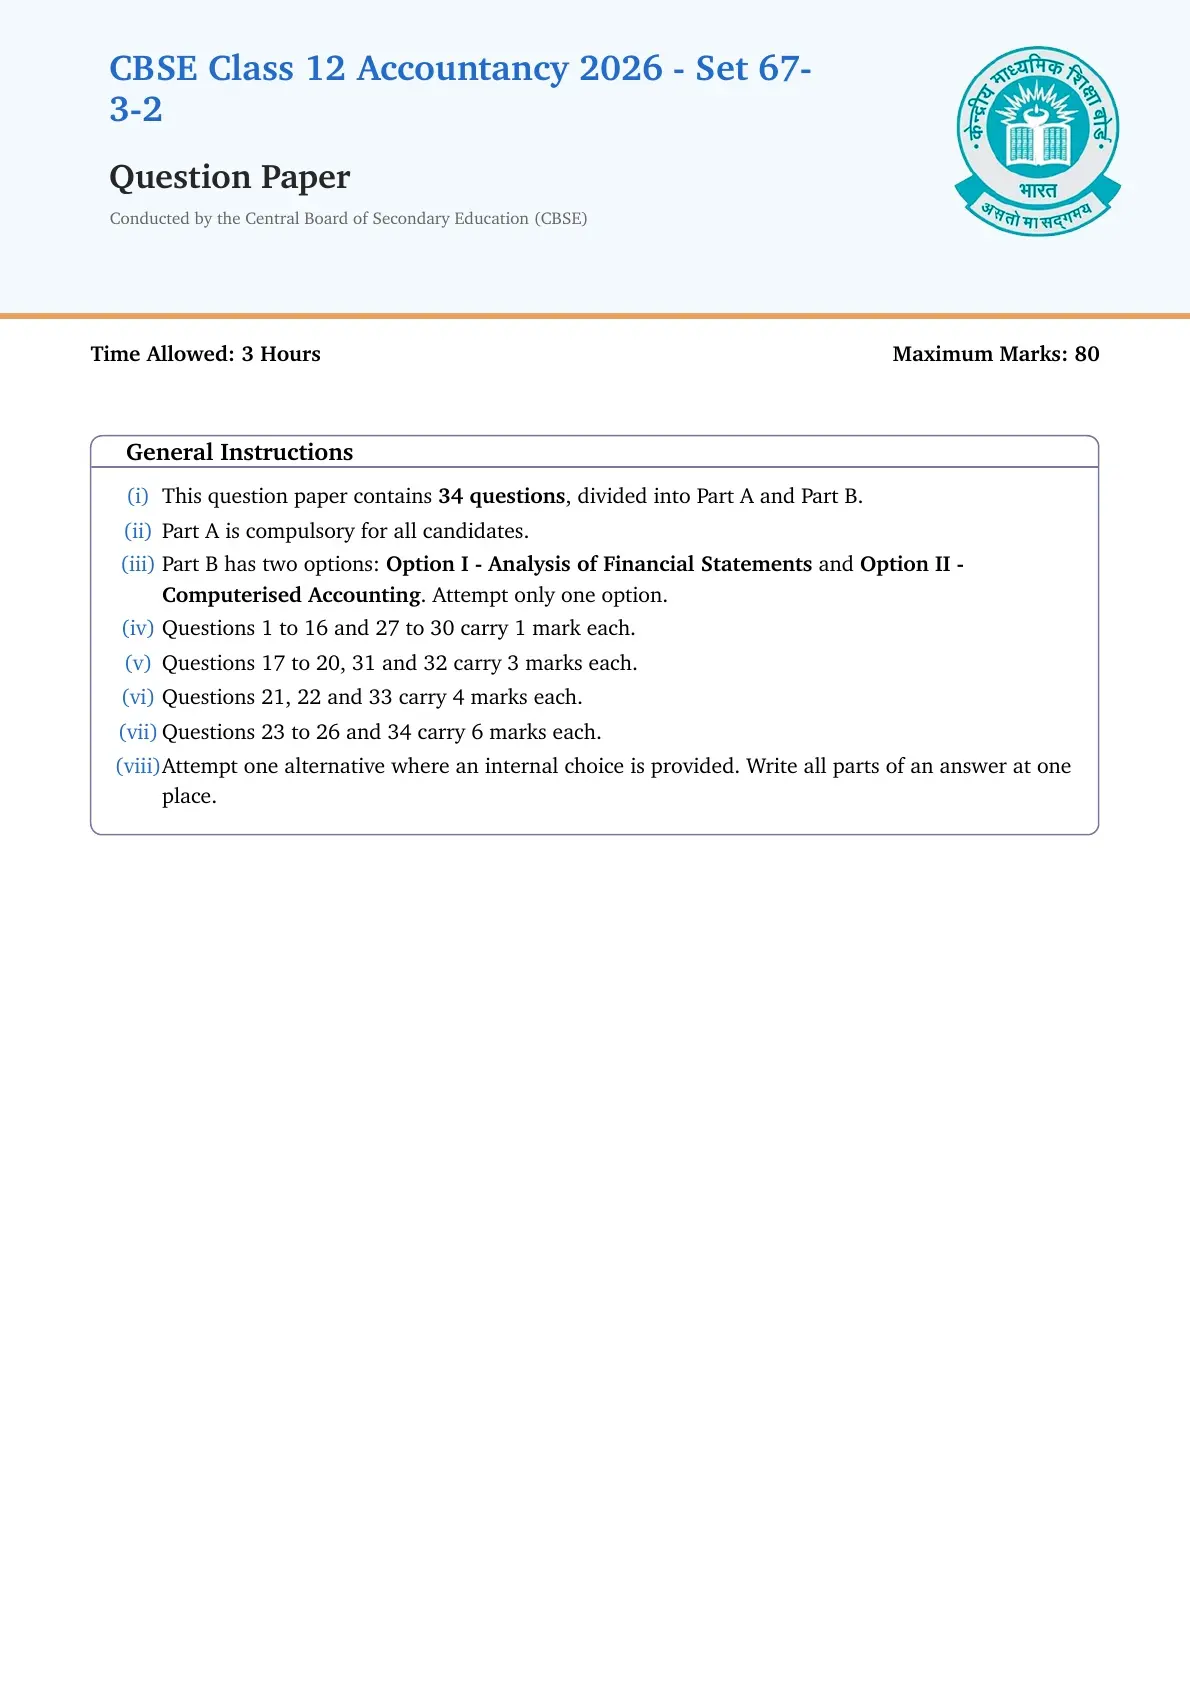
CBSE Class 12 Accountancy Question Paper 2026 Set - 2 (67/3/2) is now available for download. CBSE conducted the Class 12 Accountancy examination on Feb 24, 2026, from 10:30 AM to 1:30 PM.
Also Check: CBSE Class 12 Question Paper 2026 (All Subjects)
The question paper consists of 34 questions carrying a total of 80 marks:
- Part A is compulsory for all candidates
- Part B has two options, and candidates have to attempt only one of the given options
- Option I : Analysis of Financial Statements
- Option II : Computerised Accounting
The Accountancy question paper 2026 was rated moderately difficult by the students.
CBSE Class 12 Accountancy Set - 2(67/3/2) Question Paper 2026 with Solution Pdf
| CBSE Official PDF | CD PDF | CD PDF with Solutions |
|---|---|---|
| Download official PDF 2.38 MB | Download Collegedunia PDF 0.32 MB | – |
CBSE Class 12 Accountancy 2026 Set 2 (67/3/2) Questions with Solutions
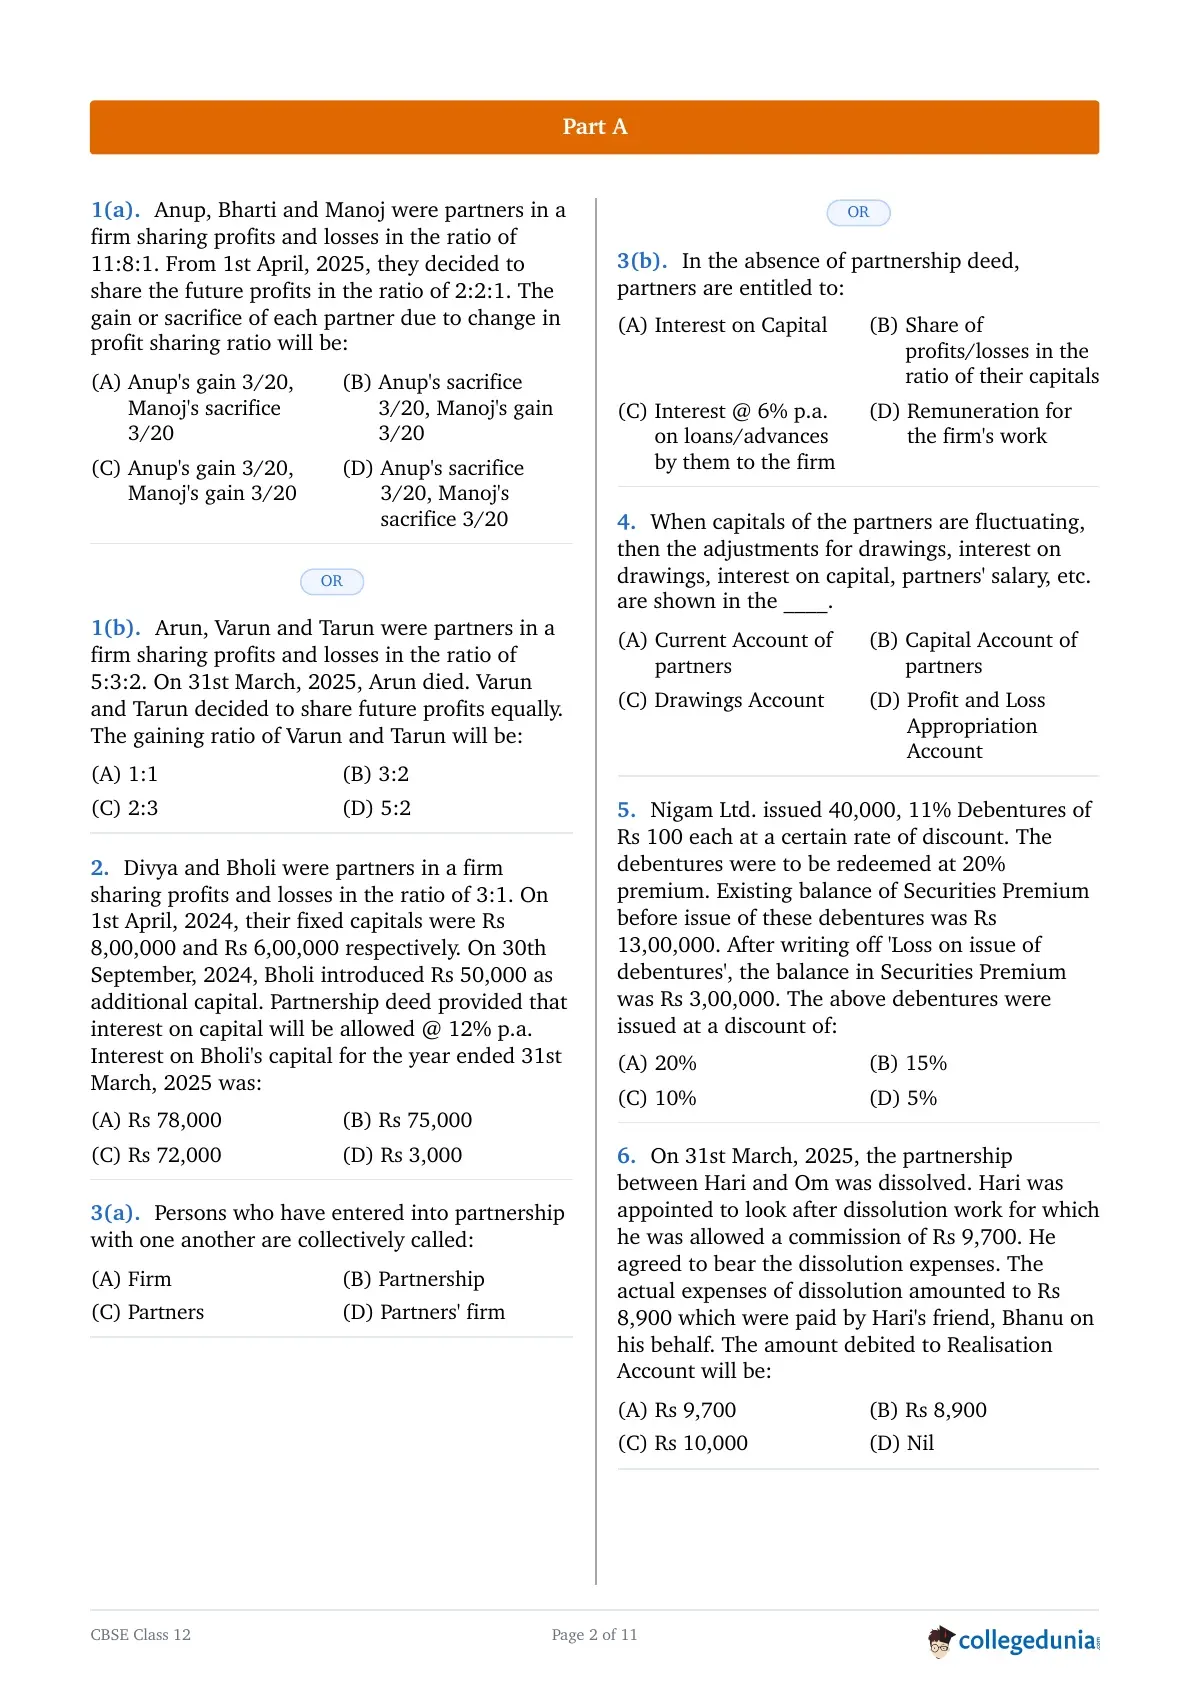
Anup, Bharti and Manoj were partners in a firm sharing profits and losses in the ratio of 11:8:1. From 1st April, 2025, they decided to share the future profits in the ratio of 2:2:1. The gain or sacrifice of each partner due to change in profit sharing ratio will be:
Arun, Varun and Tarun were partners in a firm sharing profits and losses in the ratio of 5:3:2. On 31st March, 2025, Arun died. Varun and Tarun decided to share future profits equally. The gaining ratio of Varun and Tarun will be:
Divya and Bholi were partners in a firm sharing profits and losses in the ratio of 3:1. On 1st April, 2024, their fixed capitals were Rs 8,00,000 and Rs 6,00,000 respectively. On 30th September, 2024, Bholi introduced Rs 50,000 as additional capital. Partnership deed provided that interest on capital will be allowed @ 12% p.a. Interest on Bholi's capital for the year ended 31st March, 2025 was:
Persons who have entered into partnership with one another are collectively called:
When capitals of the partners are fluctuating, then the adjustments for drawings, interest on drawings, interest on capital, partners' salary, etc. are shown in the ____.
Nigam Ltd. issued 40,000, 11% Debentures of Rs 100 each at a certain rate of discount. The debentures were to be redeemed at 20% premium. Existing balance of Securities Premium before issue of these debentures was Rs 13,00,000. After writing off 'Loss on issue of debentures', the balance in Securities Premium was Rs 3,00,000. The above debentures were issued at a discount of:
On 31st March, 2025, the partnership between Hari and Om was dissolved. Hari was appointed to look after dissolution work for which he was allowed a commission of Rs 9,700. He agreed to bear the dissolution expenses. The actual expenses of dissolution amounted to Rs 8,900 which were paid by Hari's friend, Bhanu on his behalf. The amount debited to Realisation Account will be:
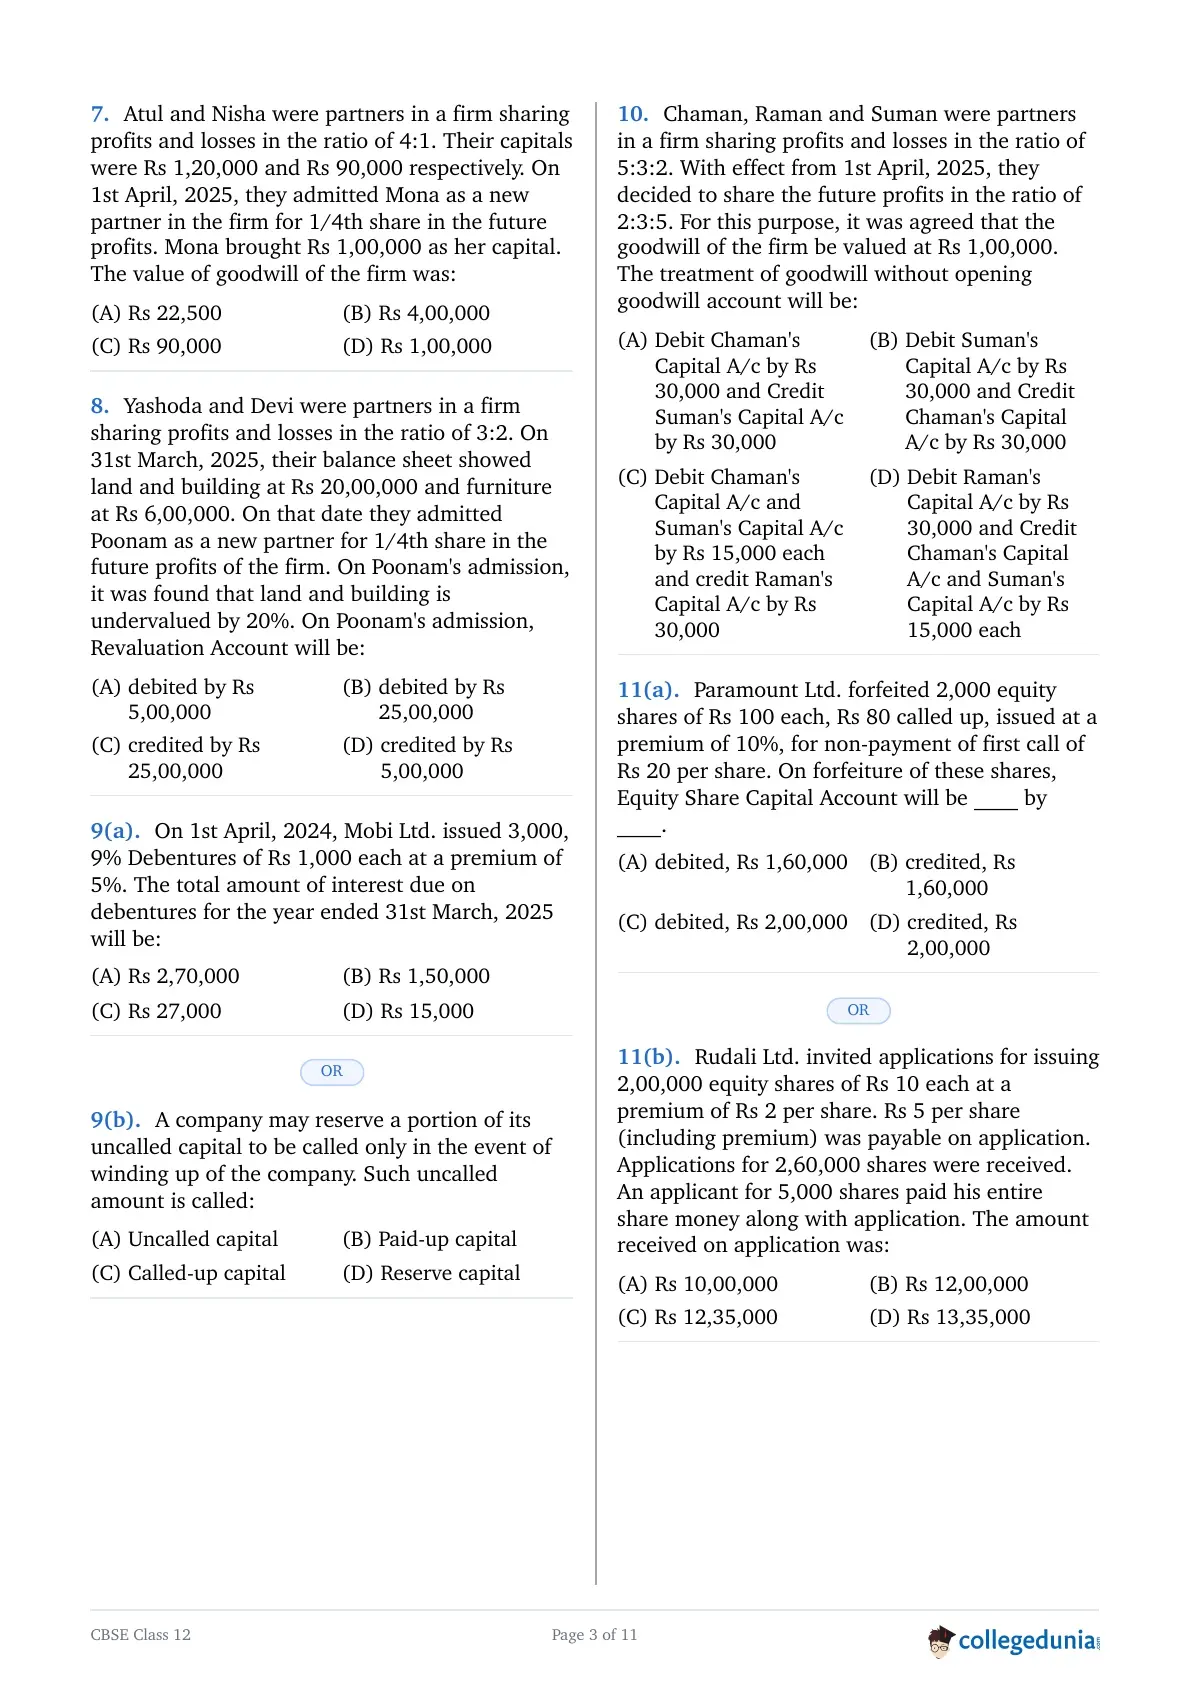
Atul and Nisha were partners in a firm sharing profits and losses in the ratio of 4:1. Their capitals were Rs 1,20,000 and Rs 90,000 respectively. On 1st April, 2025, they admitted Mona as a new partner in the firm for 1/4th share in the future profits. Mona brought Rs 1,00,000 as her capital. The value of goodwill of the firm was:
Yashoda and Devi were partners in a firm sharing profits and losses in the ratio of 3:2. On 31st March, 2025, their balance sheet showed land and building at Rs 20,00,000 and furniture at Rs 6,00,000. On that date they admitted Poonam as a new partner for 1/4th share in the future profits of the firm. On Poonam's admission, it was found that land and building is undervalued by 20%. On Poonam's admission, Revaluation Account will be:
On 1st April, 2024, Mobi Ltd. issued 3,000, 9% Debentures of Rs 1,000 each at a premium of 5%. The total amount of interest due on debentures for the year ended 31st March, 2025 will be:
A company may reserve a portion of its uncalled capital to be called only in the event of winding up of the company. Such uncalled amount is called:
Chaman, Raman and Suman were partners in a firm sharing profits and losses in the ratio of 5:3:2. With effect from 1st April, 2025, they decided to share the future profits in the ratio of 2:3:5. For this purpose, it was agreed that the goodwill of the firm be valued at Rs 1,00,000. The treatment of goodwill without opening goodwill account will be:
Paramount Ltd. forfeited 2,000 equity shares of Rs 100 each, Rs 80 called up, issued at a premium of 10%, for non-payment of first call of Rs 20 per share. On forfeiture of these shares, Equity Share Capital Account will be ____ by ____.
Rudali Ltd. invited applications for issuing 2,00,000 equity shares of Rs 10 each at a premium of Rs 2 per share. Rs 5 per share (including premium) was payable on application. Applications for 2,60,000 shares were received. An applicant for 5,000 shares paid his entire share money along with application. The amount received on application was:
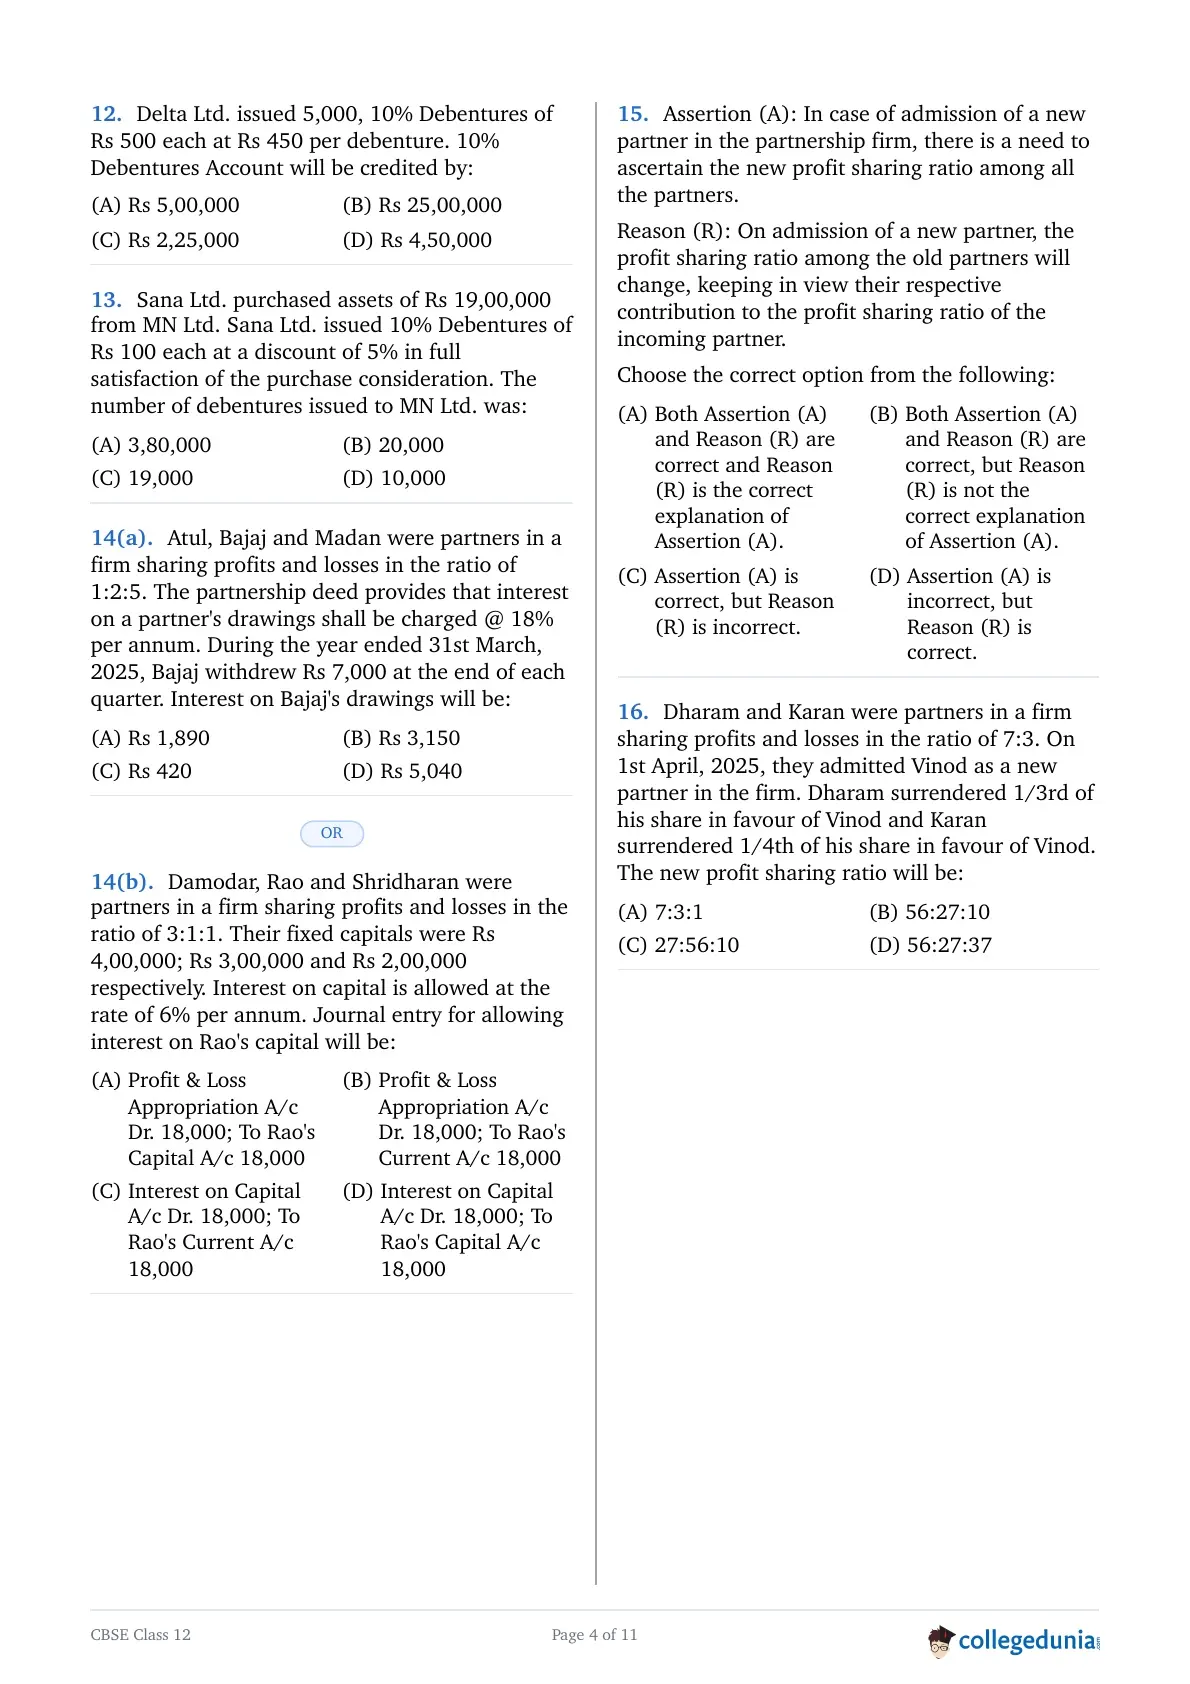
Delta Ltd. issued 5,000, 10% Debentures of Rs 500 each at Rs 450 per debenture. 10% Debentures Account will be credited by:
Sana Ltd. purchased assets of Rs 19,00,000 from MN Ltd. Sana Ltd. issued 10% Debentures of Rs 100 each at a discount of 5% in full satisfaction of the purchase consideration. The number of debentures issued to MN Ltd. was:
Atul, Bajaj and Madan were partners in a firm sharing profits and losses in the ratio of 1:2:5. The partnership deed provides that interest on a partner's drawings shall be charged @ 18% per annum. During the year ended 31st March, 2025, Bajaj withdrew Rs 7,000 at the end of each quarter. Interest on Bajaj's drawings will be:
Damodar, Rao and Shridharan were partners in a firm sharing profits and losses in the ratio of 3:1:1. Their fixed capitals were Rs 4,00,000; Rs 3,00,000 and Rs 2,00,000 respectively. Interest on capital is allowed at the rate of 6% per annum. Journal entry for allowing interest on Rao's capital will be:
Assertion (A): In case of admission of a new partner in the partnership firm, there is a need to ascertain the new profit sharing ratio among all the partners.
Reason (R): On admission of a new partner, the profit sharing ratio among the old partners will change, keeping in view their respective contribution to the profit sharing ratio of the incoming partner.
Choose the correct option from the following:
Dharam and Karan were partners in a firm sharing profits and losses in the ratio of 7:3. On 1st April, 2025, they admitted Vinod as a new partner in the firm. Dharam surrendered 1/3rd of his share in favour of Vinod and Karan surrendered 1/4th of his share in favour of Vinod. The new profit sharing ratio will be:
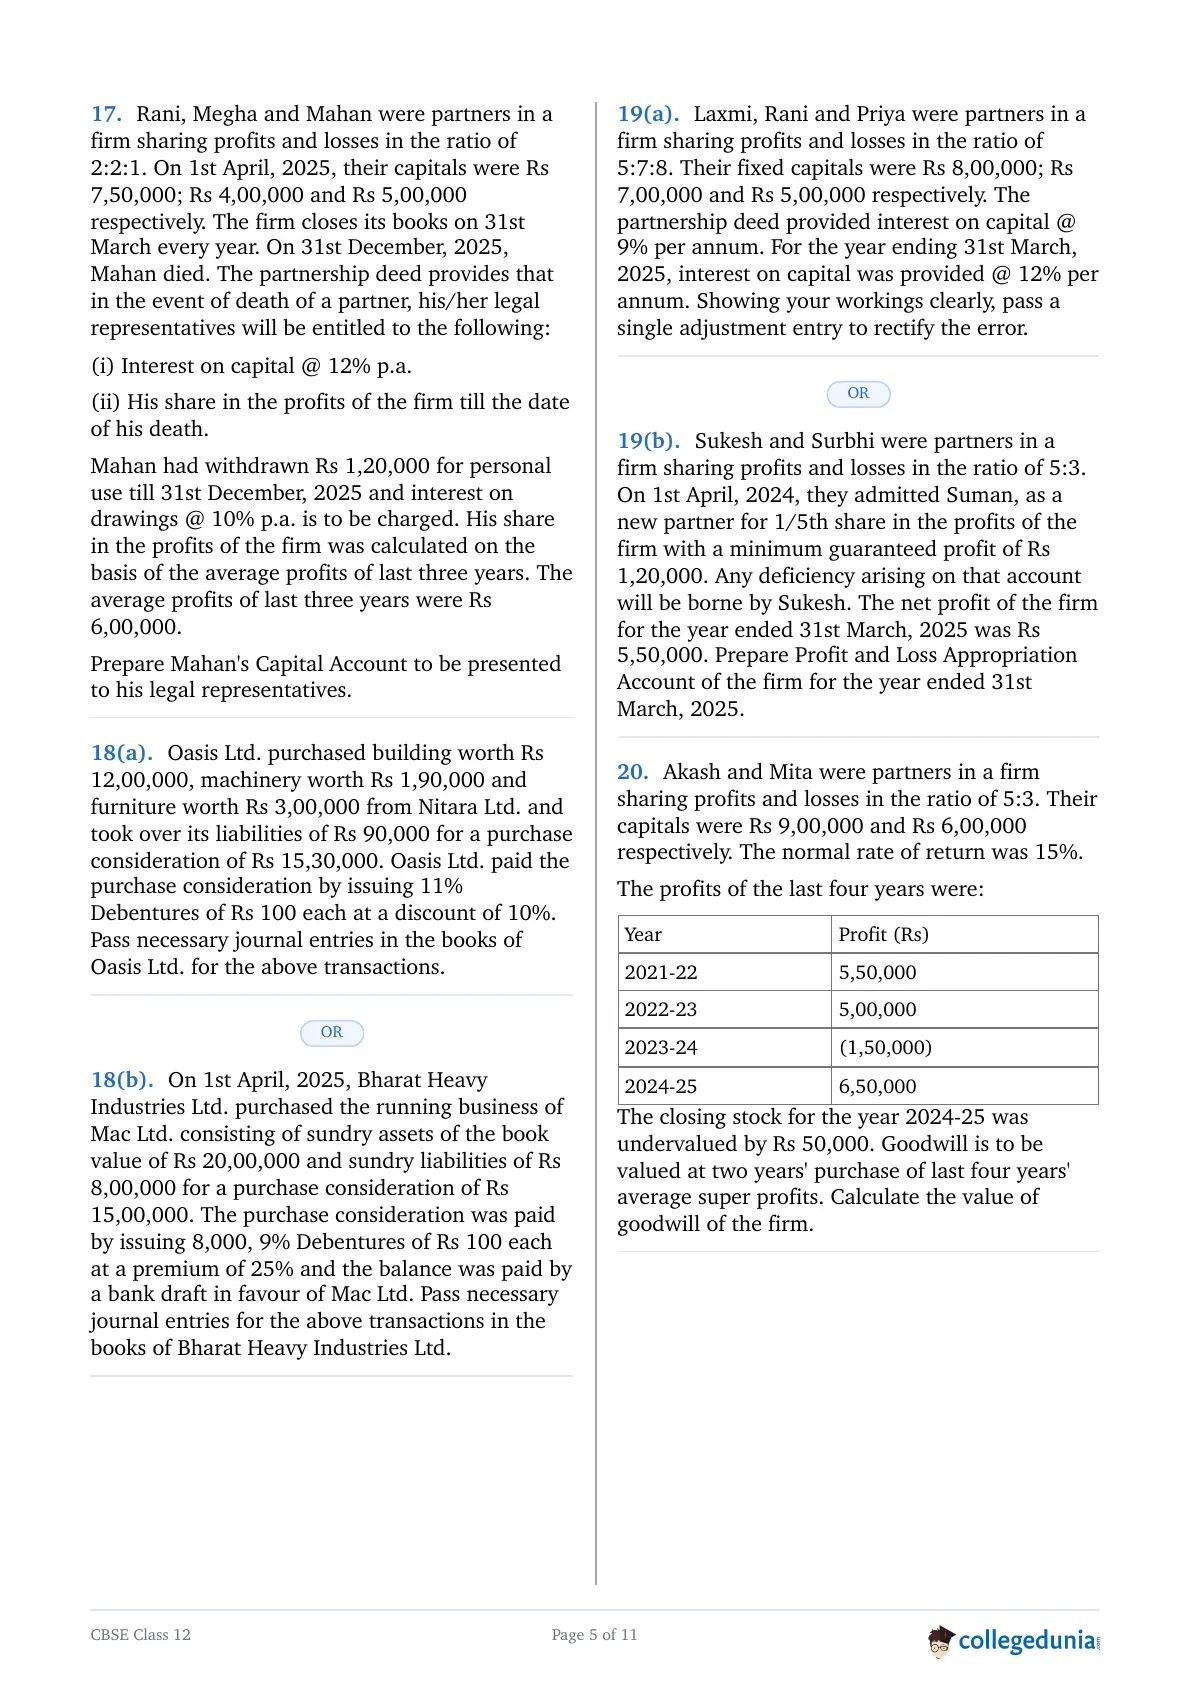
Rani, Megha and Mahan were partners in a firm sharing profits and losses in the ratio of 2:2:1. On 1st April, 2025, their capitals were Rs 7,50,000; Rs 4,00,000 and Rs 5,00,000 respectively. The firm closes its books on 31st March every year. On 31st December, 2025, Mahan died. The partnership deed provides that in the event of death of a partner, his/her legal representatives will be entitled to the following:
(i) Interest on capital @ 12% p.a.
(ii) His share in the profits of the firm till the date of his death.
Mahan had withdrawn Rs 1,20,000 for personal use till 31st December, 2025 and interest on drawings @ 10% p.a. is to be charged. His share in the profits of the firm was calculated on the basis of the average profits of last three years. The average profits of last three years were Rs 6,00,000.
Prepare Mahan's Capital Account to be presented to his legal representatives.
Oasis Ltd. purchased building worth Rs 12,00,000, machinery worth Rs 1,90,000 and furniture worth Rs 3,00,000 from Nitara Ltd. and took over its liabilities of Rs 90,000 for a purchase consideration of Rs 15,30,000. Oasis Ltd. paid the purchase consideration by issuing 11% Debentures of Rs 100 each at a discount of 10%. Pass necessary journal entries in the books of Oasis Ltd. for the above transactions.
On 1st April, 2025, Bharat Heavy Industries Ltd. purchased the running business of Mac Ltd. consisting of sundry assets of the book value of Rs 20,00,000 and sundry liabilities of Rs 8,00,000 for a purchase consideration of Rs 15,00,000. The purchase consideration was paid by issuing 8,000, 9% Debentures of Rs 100 each at a premium of 25% and the balance was paid by a bank draft in favour of Mac Ltd. Pass necessary journal entries for the above transactions in the books of Bharat Heavy Industries Ltd.
Laxmi, Rani and Priya were partners in a firm sharing profits and losses in the ratio of 5:7:8. Their fixed capitals were Rs 8,00,000; Rs 7,00,000 and Rs 5,00,000 respectively. The partnership deed provided interest on capital @ 9% per annum. For the year ending 31st March, 2025, interest on capital was provided @ 12% per annum. Showing your workings clearly, pass a single adjustment entry to rectify the error.
Sukesh and Surbhi were partners in a firm sharing profits and losses in the ratio of 5:3. On 1st April, 2024, they admitted Suman, as a new partner for 1/5th share in the profits of the firm with a minimum guaranteed profit of Rs 1,20,000. Any deficiency arising on that account will be borne by Sukesh. The net profit of the firm for the year ended 31st March, 2025 was Rs 5,50,000. Prepare Profit and Loss Appropriation Account of the firm for the year ended 31st March, 2025.
Akash and Mita were partners in a firm sharing profits and losses in the ratio of 5:3. Their capitals were Rs 9,00,000 and Rs 6,00,000 respectively. The normal rate of return was 15%.
The profits of the last four years were:
| Year | Profit (Rs) |
| 2021-22 | 5,50,000 |
| 2022-23 | 5,00,000 |
| 2023-24 | (1,50,000) |
| 2024-25 | 6,50,000 |
The closing stock for the year 2024-25 was undervalued by Rs 50,000. Goodwill is to be valued at two years' purchase of last four years' average super profits. Calculate the value of goodwill of the firm.
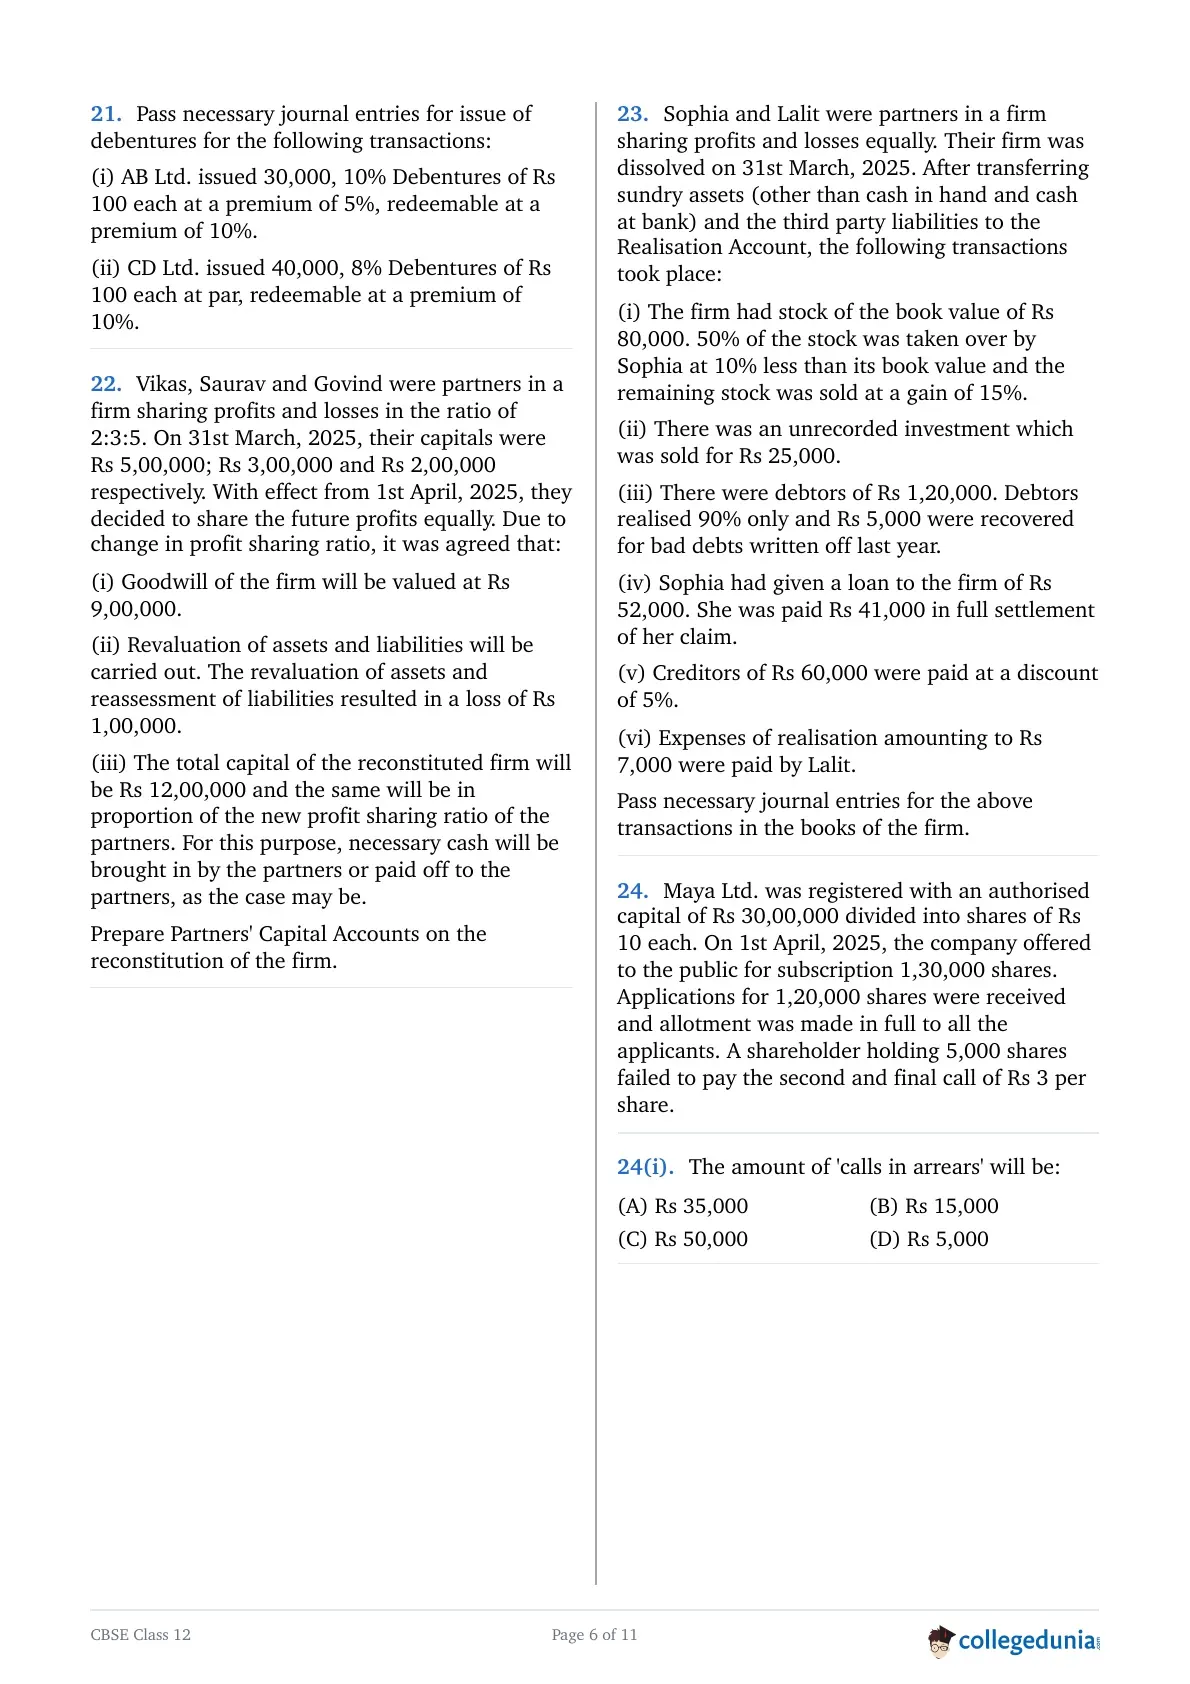
Pass necessary journal entries for issue of debentures for the following transactions:
(i) AB Ltd. issued 30,000, 10% Debentures of Rs 100 each at a premium of 5%, redeemable at a premium of 10%.
(ii) CD Ltd. issued 40,000, 8% Debentures of Rs 100 each at par, redeemable at a premium of 10%.
Vikas, Saurav and Govind were partners in a firm sharing profits and losses in the ratio of 2:3:5. On 31st March, 2025, their capitals were Rs 5,00,000; Rs 3,00,000 and Rs 2,00,000 respectively. With effect from 1st April, 2025, they decided to share the future profits equally. Due to change in profit sharing ratio, it was agreed that:
(i) Goodwill of the firm will be valued at Rs 9,00,000.
(ii) Revaluation of assets and liabilities will be carried out. The revaluation of assets and reassessment of liabilities resulted in a loss of Rs 1,00,000.
(iii) The total capital of the reconstituted firm will be Rs 12,00,000 and the same will be in proportion of the new profit sharing ratio of the partners. For this purpose, necessary cash will be brought in by the partners or paid off to the partners, as the case may be.
Prepare Partners' Capital Accounts on the reconstitution of the firm.
Sophia and Lalit were partners in a firm sharing profits and losses equally. Their firm was dissolved on 31st March, 2025. After transferring sundry assets (other than cash in hand and cash at bank) and the third party liabilities to the Realisation Account, the following transactions took place:
(i) The firm had stock of the book value of Rs 80,000. 50% of the stock was taken over by Sophia at 10% less than its book value and the remaining stock was sold at a gain of 15%.
(ii) There was an unrecorded investment which was sold for Rs 25,000.
(iii) There were debtors of Rs 1,20,000. Debtors realised 90% only and Rs 5,000 were recovered for bad debts written off last year.
(iv) Sophia had given a loan to the firm of Rs 52,000. She was paid Rs 41,000 in full settlement of her claim.
(v) Creditors of Rs 60,000 were paid at a discount of 5%.
(vi) Expenses of realisation amounting to Rs 7,000 were paid by Lalit.
Pass necessary journal entries for the above transactions in the books of the firm.
Comprehension:
Maya Ltd. was registered with an authorised capital of Rs 30,00,000 divided into shares of Rs 10 each. On 1st April, 2025, the company offered to the public for subscription 1,30,000 shares. Applications
Read More
for 1,20,000 shares were received and allotment was made in full to all the applicants. A shareholder holding 5,000 shares failed to pay the second and final call of Rs 3 per share.'Subscribed but not fully paid-up capital' of Maya Ltd. will be:
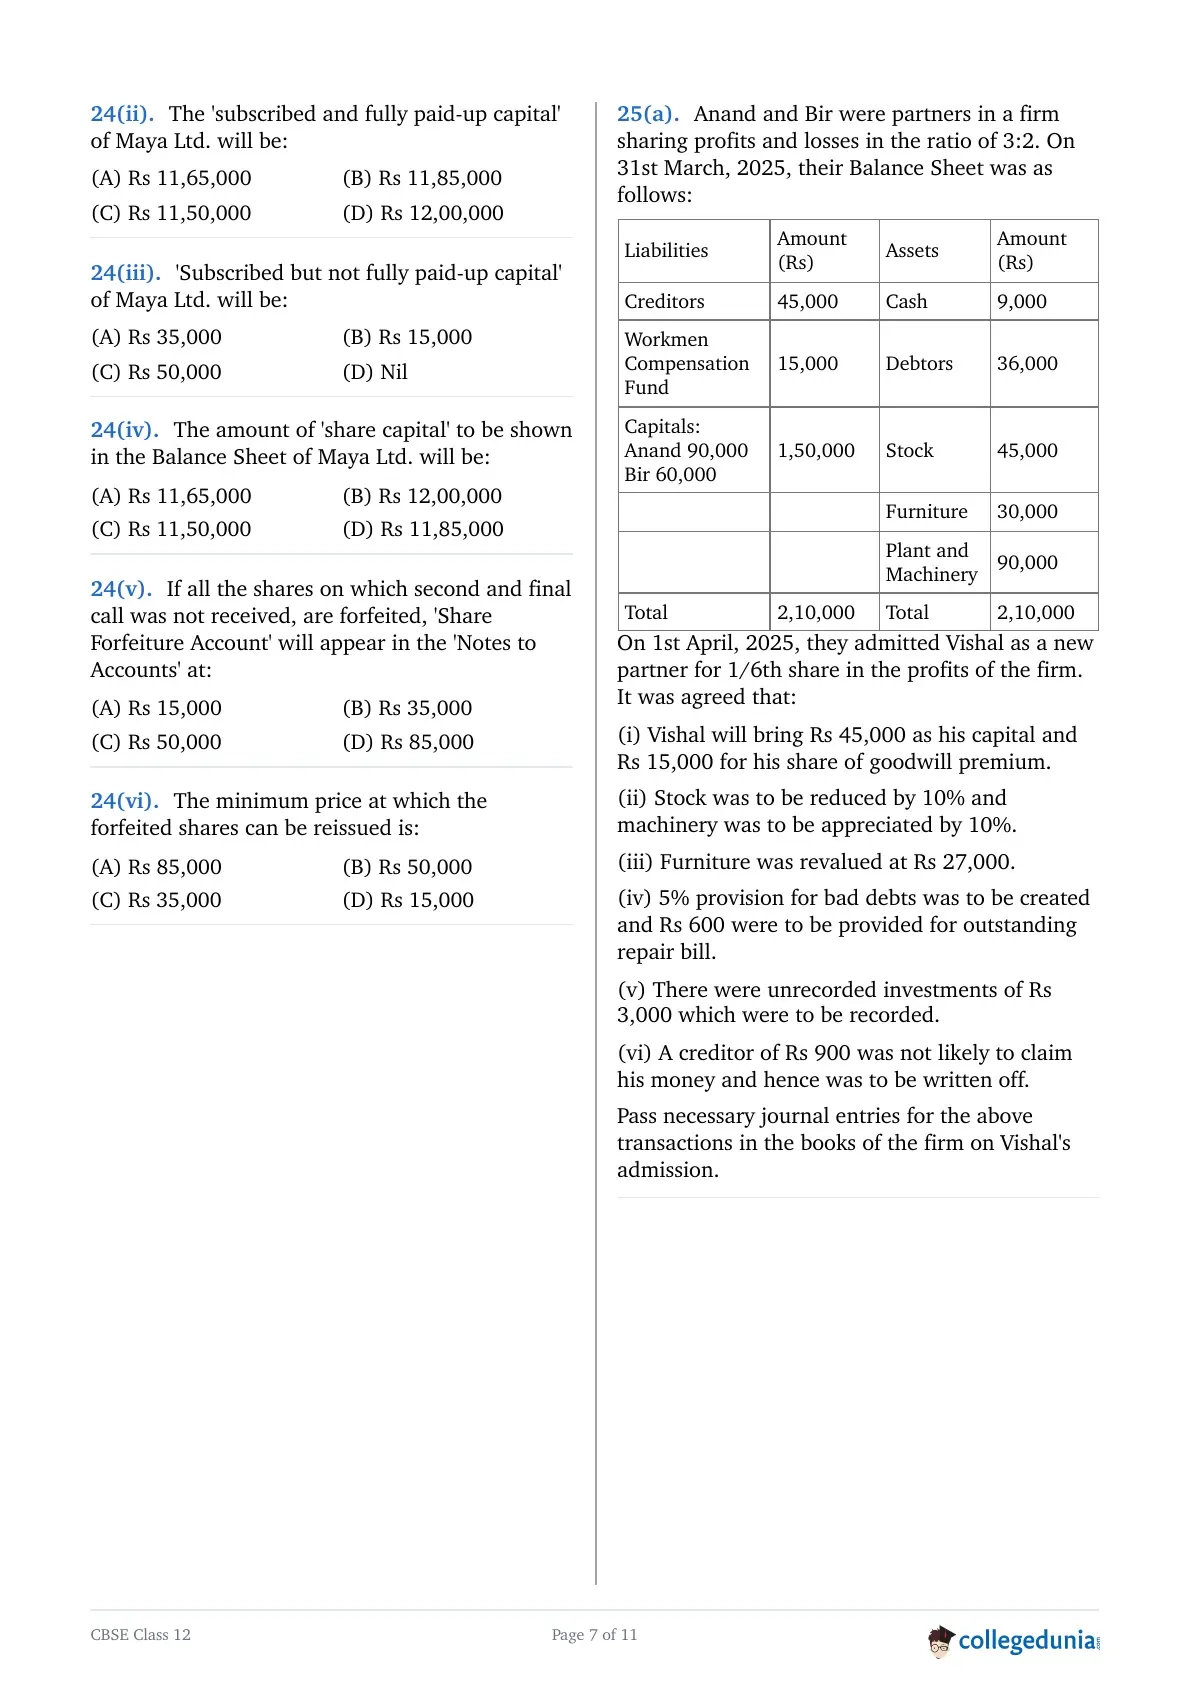
The amount of 'share capital' to be shown in the Balance Sheet of Maya Ltd. will be:
If all the shares on which second and final call was not received, are forfeited, 'Share Forfeiture Account' will appear in the 'Notes to Accounts' at:
The minimum price at which the forfeited shares can be reissued is:
Anand and Bir were partners in a firm sharing profits and losses in the ratio of 3:2. On 31st March, 2025, their Balance Sheet was as follows:
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
| Creditors | 45,000 | Cash | 9,000 |
| Workmen Compensation Fund | 15,000 | Debtors | 36,000 |
| Capitals: Anand 90,000 Bir 60,000 | 1,50,000 | Stock | 45,000 |
| Furniture | 30,000 | ||
| Plant and Machinery | 90,000 | ||
| Total | 2,10,000 | Total | 2,10,000 |
On 1st April, 2025, they admitted Vishal as a new partner for 1/6th share in the profits of the firm. It was agreed that:
(i) Vishal will bring Rs 45,000 as his capital and Rs 15,000 for his share of goodwill premium.
(ii) Stock was to be reduced by 10% and machinery was to be appreciated by 10%.
(iii) Furniture was revalued at Rs 27,000.
(iv) 5% provision for bad debts was to be created and Rs 600 were to be provided for outstanding repair bill.
(v) There were unrecorded investments of Rs 3,000 which were to be recorded.
(vi) A creditor of Rs 900 was not likely to claim his money and hence was to be written off.
Pass necessary journal entries for the above transactions in the books of the firm on Vishal's admission.
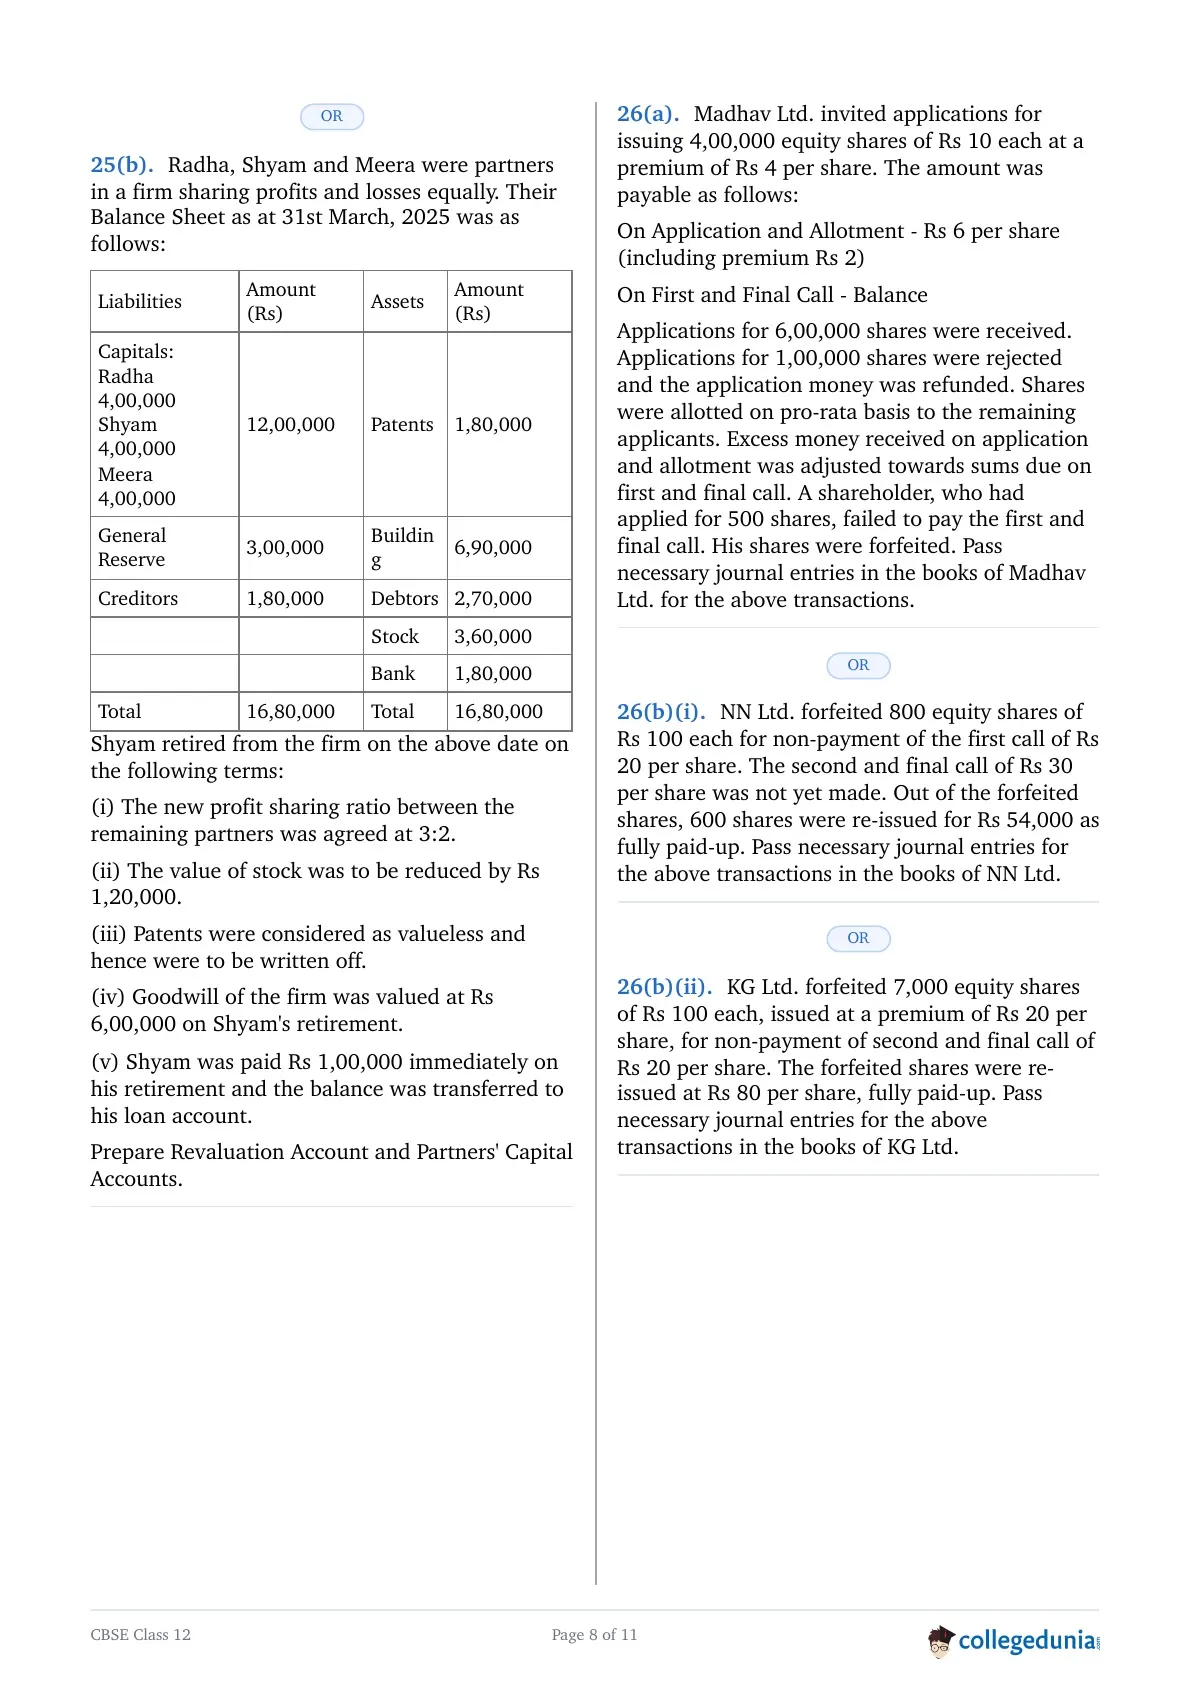
Radha, Shyam and Meera were partners in a firm sharing profits and losses equally. Their Balance Sheet as at 31st March, 2025 was as follows:
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
| Capitals: Radha 4,00,000 Shyam 4,00,000 Meera 4,00,000 | 12,00,000 | Patents | 1,80,000 |
| General Reserve | 3,00,000 | Building | 6,90,000 |
| Creditors | 1,80,000 | Debtors | 2,70,000 |
| Stock | 3,60,000 | ||
| Bank | 1,80,000 | ||
| Total | 16,80,000 | Total | 16,80,000 |
Shyam retired from the firm on the above date on the following terms:
(i) The new profit sharing ratio between the remaining partners was agreed at 3:2.
(ii) The value of stock was to be reduced by Rs 1,20,000.
(iii) Patents were considered as valueless and hence were to be written off.
(iv) Goodwill of the firm was valued at Rs 6,00,000 on Shyam's retirement.
(v) Shyam was paid Rs 1,00,000 immediately on his retirement and the balance was transferred to his loan account.
Prepare Revaluation Account and Partners' Capital Accounts.
Madhav Ltd. invited applications for issuing 4,00,000 equity shares of Rs 10 each at a premium of Rs 4 per share. The amount was payable as follows:
On Application and Allotment - Rs 6 per share (including premium Rs 2)
On First and Final Call - Balance
Applications for 6,00,000 shares were received. Applications for 1,00,000 shares were rejected and the application money was refunded. Shares were allotted on pro-rata basis to the remaining applicants. Excess money received on application and allotment was adjusted towards sums due on first and final call. A shareholder, who had applied for 500 shares, failed to pay the first and final call. His shares were forfeited. Pass necessary journal entries in the books of Madhav Ltd. for the above transactions.
NN Ltd. forfeited 800 equity shares of Rs 100 each for non-payment of the first call of Rs 20 per share. The second and final call of Rs 30 per share was not yet made. Out of the forfeited shares, 600 shares were re-issued for Rs 54,000 as fully paid-up. Pass necessary journal entries for the above transactions in the books of NN Ltd.
KG Ltd. forfeited 7,000 equity shares of Rs 100 each, issued at a premium of Rs 20 per share, for non-payment of second and final call of Rs 20 per share. The forfeited shares were re-issued at Rs 80 per share, fully paid-up. Pass necessary journal entries for the above transactions in the books of KG Ltd.
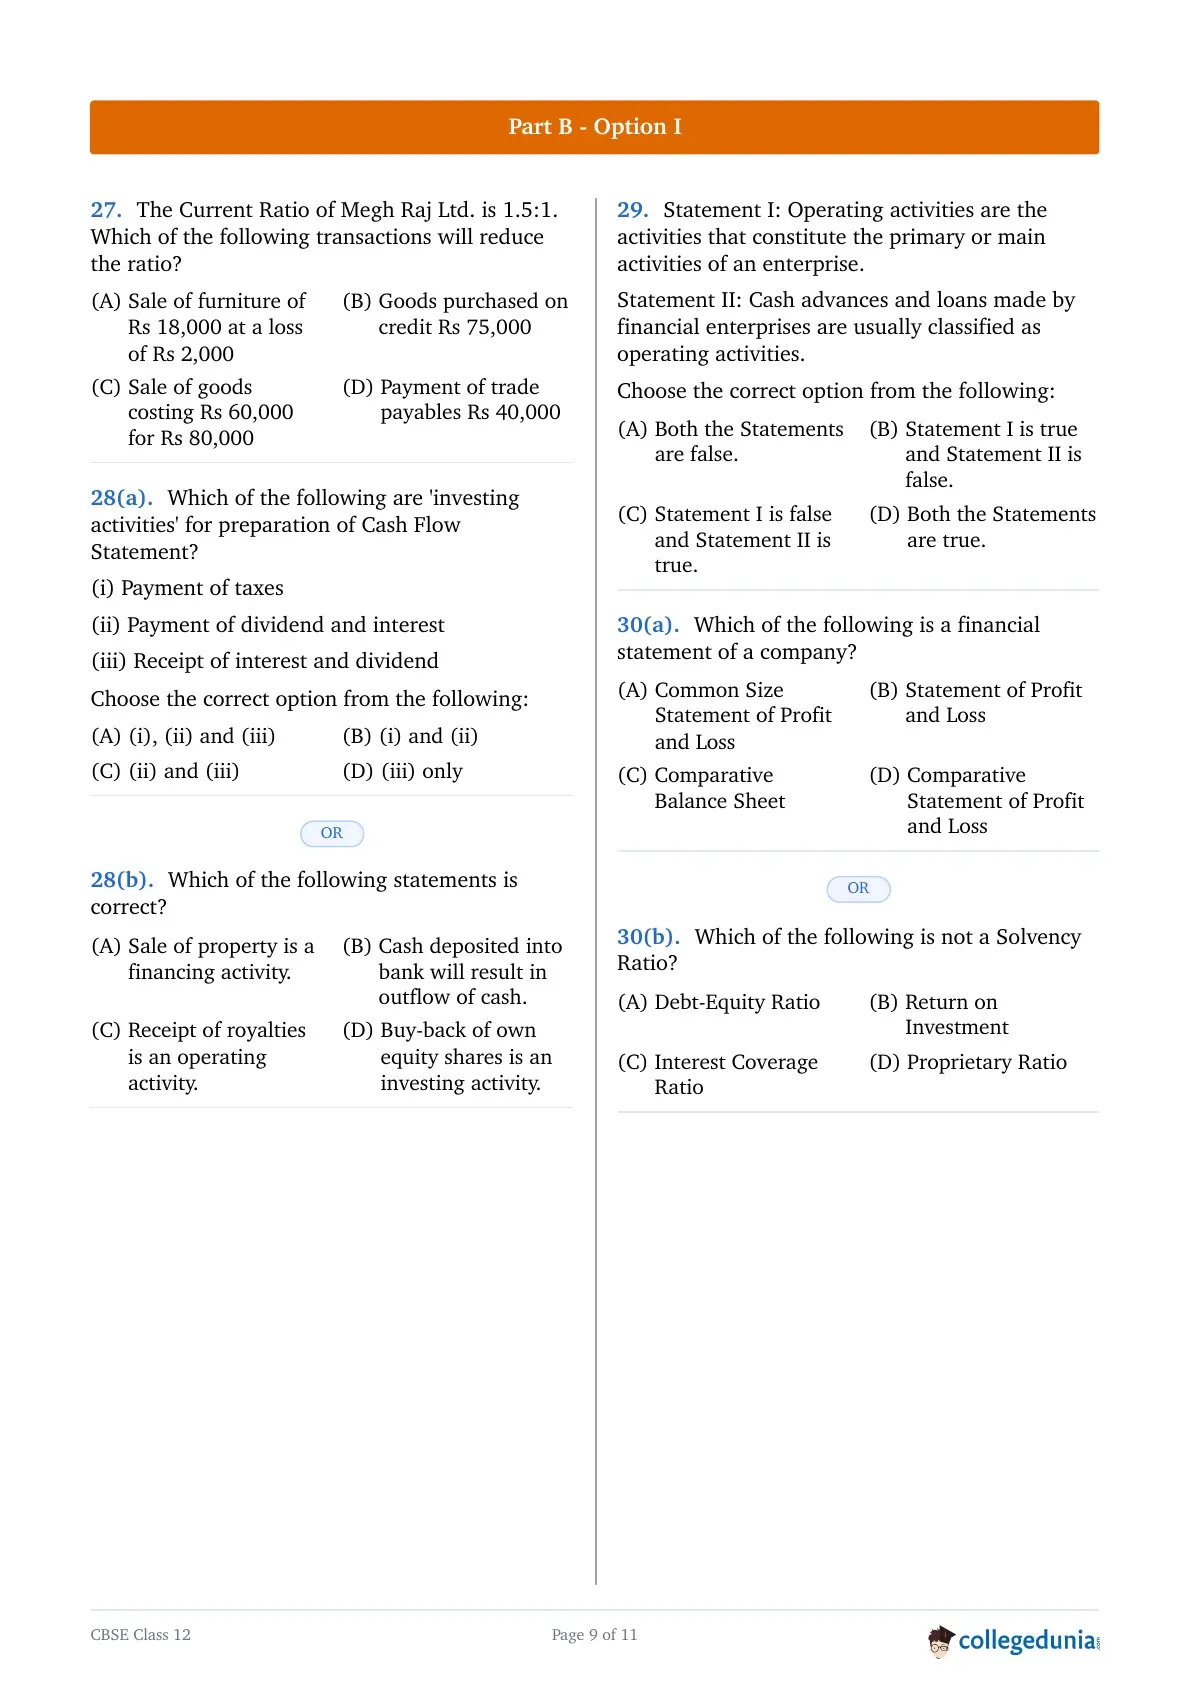
The Current Ratio of Megh Raj Ltd. is 1.5:1. Which of the following transactions will reduce the ratio?
Which of the following are 'investing activities' for preparation of Cash Flow Statement?
(i) Payment of taxes
(ii) Payment of dividend and interest
(iii) Receipt of interest and dividend
Choose the correct option from the following:
Statement I: Operating activities are the activities that constitute the primary or main activities of an enterprise.
Statement II: Cash advances and loans made by financial enterprises are usually classified as operating activities.
Choose the correct option from the following:
Which of the following is a financial statement of a company?
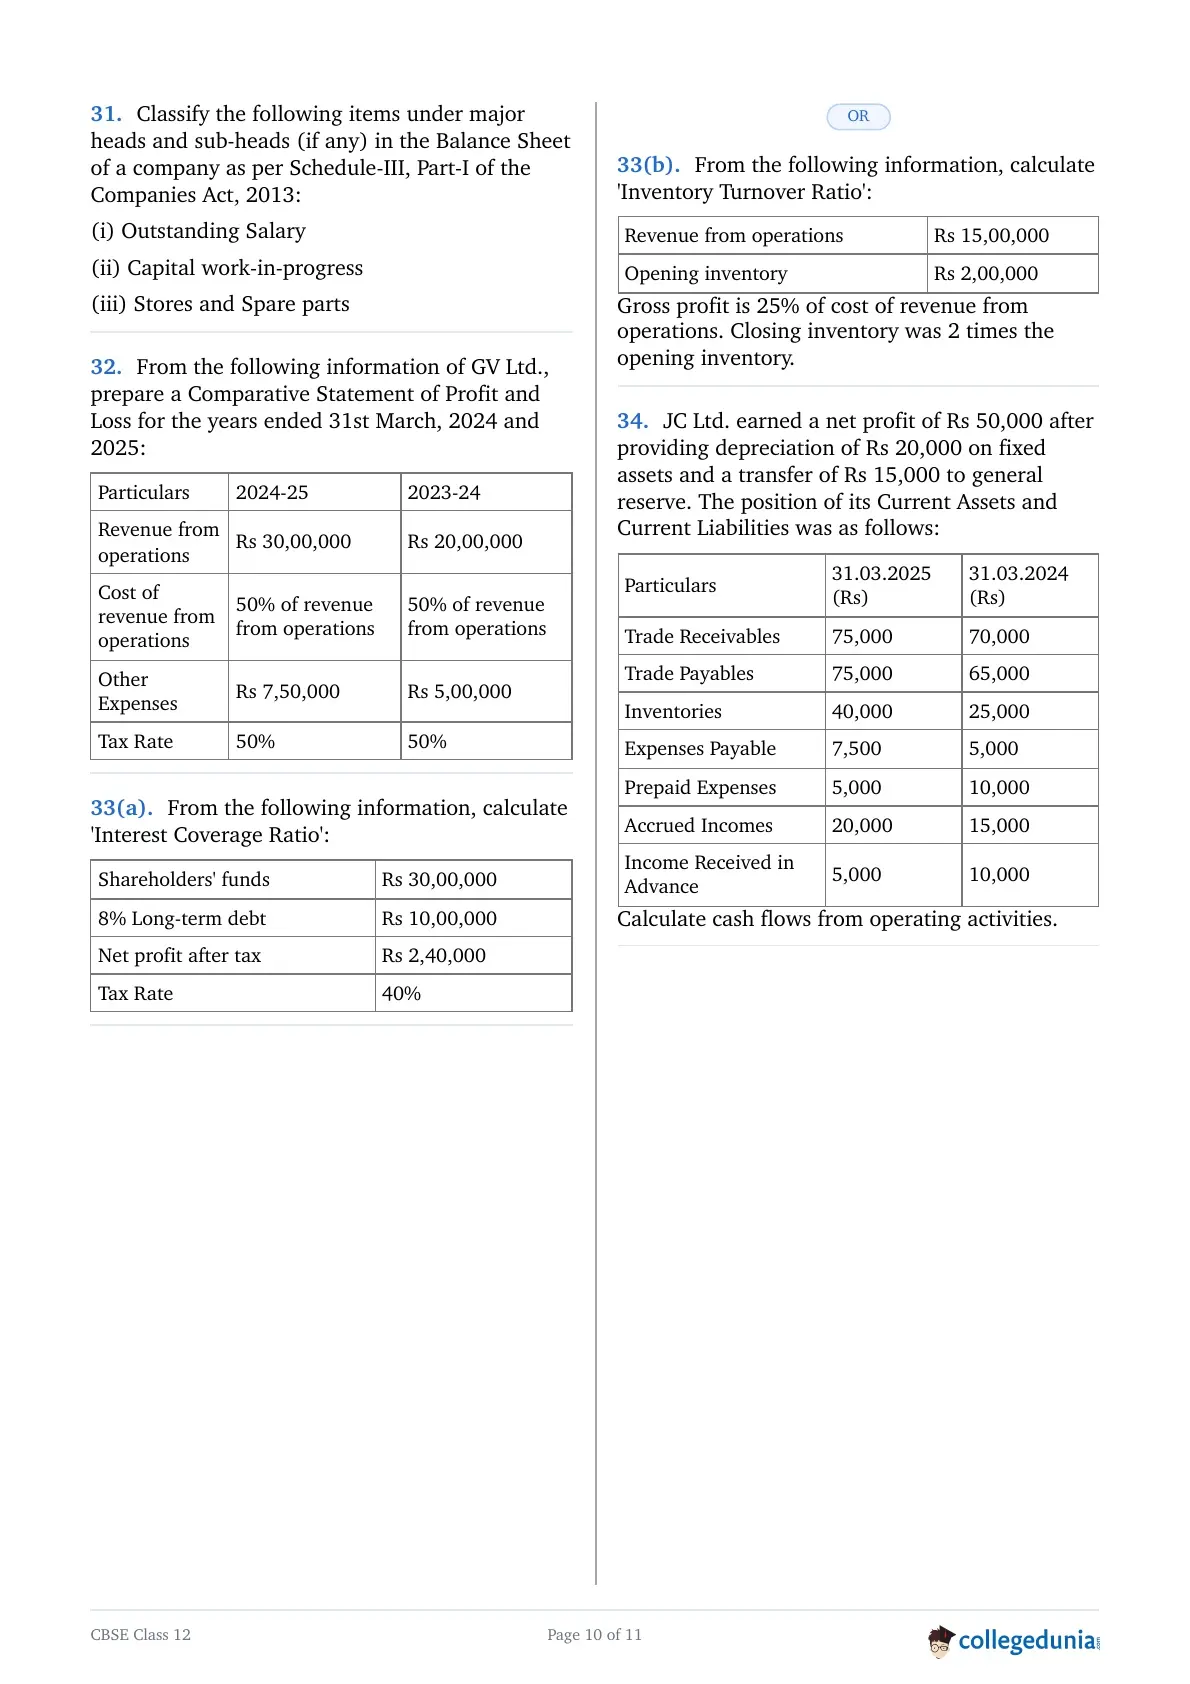
Classify the following items under major heads and sub-heads (if any) in the Balance Sheet of a company as per Schedule-III, Part-I of the Companies Act, 2013:
(i) Outstanding Salary
(ii) Capital work-in-progress
(iii) Stores and Spare parts
From the following information of GV Ltd., prepare a Comparative Statement of Profit and Loss for the years ended 31st March, 2024 and 2025:
| Particulars | 2024-25 | 2023-24 |
| Revenue from operations | Rs 30,00,000 | Rs 20,00,000 |
| Cost of revenue from operations | 50% of revenue from operations | 50% of revenue from operations |
| Other Expenses | Rs 7,50,000 | Rs 5,00,000 |
| Tax Rate | 50% | 50% |
From the following information, calculate 'Interest Coverage Ratio':
| Shareholders' funds | Rs 30,00,000 |
| 8% Long-term debt | Rs 10,00,000 |
| Net profit after tax | Rs 2,40,000 |
| Tax Rate | 40% |
From the following information, calculate 'Inventory Turnover Ratio':
| Revenue from operations | Rs 15,00,000 |
| Opening inventory | Rs 2,00,000 |
Gross profit is 25% of cost of revenue from operations. Closing inventory was 2 times the opening inventory.
JC Ltd. earned a net profit of Rs 50,000 after providing depreciation of Rs 20,000 on fixed assets and a transfer of Rs 15,000 to general reserve. The position of its Current Assets and Current Liabilities was as follows:
| Particulars | 31.03.2025 (Rs) | 31.03.2024 (Rs) |
| Trade Receivables | 75,000 | 70,000 |
| Trade Payables | 75,000 | 65,000 |
| Inventories | 40,000 | 25,000 |
| Expenses Payable | 7,500 | 5,000 |
| Prepaid Expenses | 5,000 | 10,000 |
| Accrued Incomes | 20,000 | 15,000 |
| Income Received in Advance | 5,000 | 10,000 |
Calculate cash flows from operating activities.
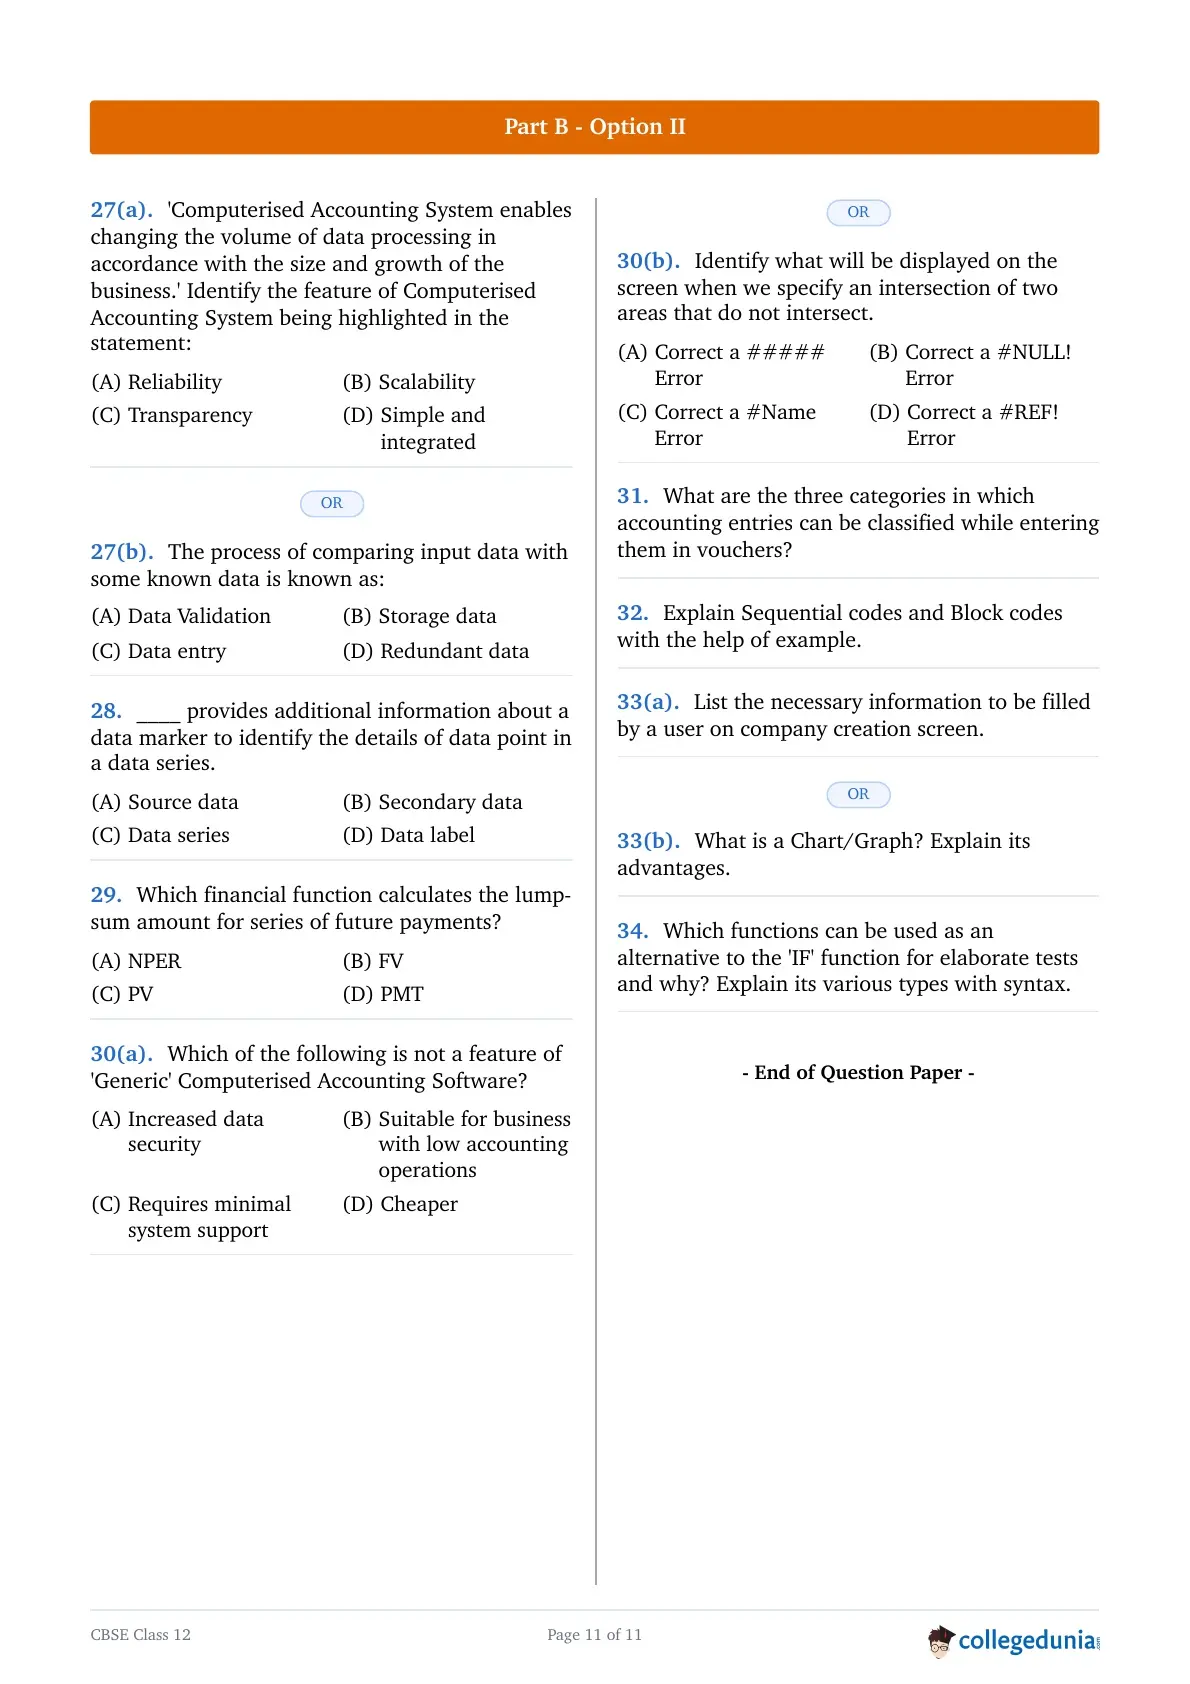
'Computerised Accounting System enables changing the volume of data processing in accordance with the size and growth of the business.' Identify the feature of Computerised Accounting System being highlighted in the statement:
The process of comparing input data with some known data is known as:
____ provides additional information about a data marker to identify the details of data point in a data series.
Which financial function calculates the lump-sum amount for series of future payments?
Which of the following is not a feature of 'Generic' Computerised Accounting Software?
Identify what will be displayed on the screen when we specify an intersection of two areas that do not intersect.
What are the three categories in which accounting entries can be classified while entering them in vouchers?
Explain Sequential codes and Block codes with the help of example.
List the necessary information to be filled by a user on company creation screen.
Which functions can be used as an alternative to the 'IF' function for elaborate tests and why? Explain its various types with syntax.
CBSE Class 12 Accountancy Question Paper Pattern and Marking Scheme
The CBSE Class 12 Accountancy 2026 theory paper is of 80 marks and has 34 questions, all compulsory: Part A (60 marks) is common and Part B (20 marks) has two options, Option I (Analysis of Financial Statements) and Option II (Computerised Accounting), of which a candidate attempts only one. Internal choice (OR) is given in several questions. The tables below give the paper pattern and the marking rules from the official CBSE question paper and marking scheme.
CBSE Class 12 Accountancy Question Paper Pattern 2026
| Part | Questions | Question Type | Marks per Question | Marks |
|---|---|---|---|---|
| Part A | Q1 - Q16 | Multiple choice questions (MCQs) | 1 | 16 |
| Part A | Q17 - Q20 | Short answer questions | 3 | 12 |
| Part A | Q21 - Q22 | Short answer questions | 4 | 8 |
| Part A | Q23 | Long answer questions | 6 | 6 |
| Part A | Q24 | Case-based questions (6 MCQs of 1 mark each) | 1 | 6 |
| Part A | Q25 - Q26 | Long answer questions | 6 | 12 |
| Part B | Q27 - Q30 | Multiple choice questions (MCQs) | 1 | 4 |
| Part B | Q31 - Q32 | Short answer questions | 3 | 6 |
| Part B | Q33 | Short answer questions | 4 | 4 |
| Part B | Q34 | Long answer questions | 6 | 6 |
| Total | 34 questions | 80 |
CBSE Class 12 Accountancy Marking Scheme 2026
| Marking point | How it is applied |
|---|---|
| Value-point marking | Marks are awarded against the value points (steps) given in the official marking scheme; the marks of an answer are split across its parts and value points. |
| Own expression | The marking scheme carries suggested value points only. A correct answer in the student's own words is awarded due marks. |
| Competency-based questions | If a competency-based answer is not from the marking scheme but shows the correct competency, due marks are awarded. |
| Errors | An error is penalised only once; no marks are deducted for its cumulative effect. |
| Incorrect answer | A totally incorrect answer is awarded zero (0) marks. |
| Choice (OR) questions | If both options of a question with internal choice are attempted, marks are awarded for both and the higher score is taken; if only one option is attempted, the other is marked NA (not attempted). |
| Part B options | If a candidate attempts both Option I and Option II of Part B, the higher of the two scores is taken and the other response is disregarded. |
| Scale of marks | The full scale of 0 to 80 marks is used and full marks are awarded whenever the answer deserves them. |
CBSE Class 12 Accountancy Unit-Wise Weightage
| Part | Units / Chapters | Marks |
|---|---|---|
| Part A – Accounting for Partnership Firms and Companies (60 Marks) | Fundamentals of Partnership Firms | 6 |
| Reconstitution of Partnership (Admission, Retirement, Death, Change in Ratio) | 18 | |
| Dissolution of Partnership Firm | 6 | |
| Accounting for Share Capital | 8 | |
| Accounting for Debentures | 12 | |
| Total Part A | — | 60 |
| Part B – Financial Statement Analysis OR Computerised Accounting (20 Marks) | Analysis of Financial Statements (including Cash Flow Statement, Ratio Analysis) OR Computerised Accounting | 20 |
| Total Part B | — | 20 |
| Part C – Project Work | Project File (12) + Viva Voce (8) | 20 |
| Grand Total | — | 100 |


Comments